A debt consolidation calculator spreadsheet compares three paths side by side: keep the cards, refinance with a personal loan, or move balances to a 0 percent transfer card. On a typical $18,000 three-card profile at a 23.6 percent blended rate, a 13 percent personal loan or a 0 percent transfer cuts total interest by roughly $4,900 to $7,400, as long as the monthly payment stays high. The math works only when the new rate plus fees clears the current rate by enough margin, and the spreadsheet shows in dollars when it doesn't.
The pitch for consolidation is simple: one payment instead of three, a lower rate, faster payoff. The catch is in three places - the fees, the term length, and what happens to the old cards once the balances hit zero. A spreadsheet doesn’t fix the behavior problem, but it tells you in dollars whether the math even works before you sign anything.
This guide walks through a debt consolidation calculator spreadsheet that models the three scenarios with realistic numbers. It uses the kind of debt profile that actually shows up on consolidation quotes: three credit cards at $4,000, $6,000, and $8,000, sitting at APRs between 21 and 25 percent. Per the Federal Reserve’s G.19 release for Q1 2026, the average credit card APR across all accounts is 21.0 percent. The average 24-month personal loan APR is 11.4 percent. That gap is where consolidation either works or doesn’t.
The simple version of “does consolidation help?”
There’s one comparison that matters. You have today’s weighted-average rate on your cards. The consolidation offer has a new rate plus a fee. If (new rate + amortized fee) < (current weighted rate) by enough margin to also cover the longer or different repayment term, consolidation saves money. If not, it doesn’t.
Everything else in the spreadsheet is sizing that gap and translating it to dollars. The arithmetic is grade-school; the temptation is to skip it because the lender’s brochure already did “the math” for you.
The three scenarios
A useful debt consolidation spreadsheet runs three side-by-side payoff timelines:
- Keep existing. Each card stays where it is. You pay minimums plus whatever extra you can afford, applied either evenly or to a target debt.
- Personal loan consolidation. A single fixed-rate loan pays off all the cards on day one. You make one new payment for a fixed number of months until it’s gone.
- Balance transfer. Balances move to a new card with a promotional rate (often 0 percent for 12 to 21 months). After the promo expires, the remaining balance reverts to the card’s standard APR.
Each scenario produces a total interest figure and a total time-to-debt-free. Seeing all three on one screen is the only way the comparison stays honest.
The inputs
Five inputs drive everything. Get these right and the calculator does its job.
| Input | Where to find it | Typical range |
|---|---|---|
| Each card’s balance | Most recent statement | $500 to $30,000+ |
| Each card’s APR | Statement, “interest rates and charges” section | 18 to 29.99 percent |
| Each card’s minimum payment | Statement | 1 to 3 percent of balance or $25, whichever is greater |
| Personal loan offer (rate, term, fee) | Lender’s pre-approval | 8 to 24 percent APR, 24 to 60 months, 1 to 8 percent origination fee |
| Balance transfer offer (promo rate, promo length, transfer fee, post-promo rate) | Card offer page | 0 percent for 12 to 21 months, 3 to 5 percent fee, 20+ percent post-promo |
Per the CFPB’s guidance on credit card consolidation, the post-promo rate on a balance transfer is the part that catches people. The 0 percent looks great until month 13.
The worked example
A realistic three-card profile:
| Debt | Balance | APR | Minimum |
|---|---|---|---|
| Card A | $4,000 | 21.0% | $80 |
| Card B | $6,000 | 23.5% | $120 |
| Card C | $8,000 | 24.99% | $160 |
| Total | $18,000 | 23.6% weighted | $360 |
The weighted-average APR is 23.6 percent. That’s the number consolidation has to beat by enough margin to be worth the paperwork.
Assume $200 a month of extra payment available beyond minimums, for a total monthly outlay of $560.
Scenario 1: keep existing, avalanche order
Paying $560 a month, applied to the highest-rate card first (Card C, 24.99%), then rolling into Card B, then Card A:
- Months to debt-free: about 50
- Total interest paid: about $9,990
Scenario 2: personal loan at 13 percent for 48 months, 3 percent origination fee
The lender charges a 3 percent origination fee out of the proceeds. To land $18,000 against the cards, you borrow about $18,557, of which roughly $557 is the fee. The monthly payment on $18,557 at 13 percent for 48 months is about $498.
- Months to debt-free: 48
- Total interest paid: about $5,340 on the loan; counting the $557 fee, the total cost of clearing the $18,000 is about $5,900
Net result vs scenario 1: roughly $4,100 cheaper, and at a lower monthly payment ($498 vs $560), because the drop from a 23.6 percent blended rate to 13 percent outweighs the slightly longer term. This is the case consolidation is built for: a wide rate spread on a balance large enough for the spread to matter.
If you keep paying $560 a month (the same outlay as scenario 1) instead of the contractual $498:
- Months to debt-free: about 42
- Total interest paid: about $4,560 on the loan (about $5,110 counting the fee)
That’s about $4,880 of savings vs scenario 1. Keeping the higher payment doesn’t create the savings here; the rate cut does that on its own. It just banks the same rate cut a few months faster instead of stretching it across the full 48-month term.
Scenario 3: balance transfer, 0 percent for 18 months, 4 percent fee, 24.99 percent after
A 4 percent transfer fee on $18,000 is $720, added to the balance, so you start with $18,720 at 0 percent.
If you pay $560 a month for the 18-month promo period:
- Paid during promo: $10,080
- Balance at month 19: $8,640 at 24.99%
- Months to clear the remainder at $560/mo: about 19 more months
- Total months: about 37
- Total interest paid: about $1,890 (mostly post-promo); with the $720 fee, total cost is about $2,610
Faster payoff than the other scenarios and the lowest total interest of the three, if you keep the $560 monthly payment going through the promo period.
If instead you “celebrate” the 0 percent by paying only $360 a month (the old minimum total) during the promo:
- Paid during promo: $6,480
- Balance at month 19: $12,240 at 24.99%
- Total interest paid post-promo: about $9,270
- Total months to debt-free: about 78
That’s worse than every other scenario, scenario 1 included. The 0 percent promo isn’t a free ride; it’s a window. Coast through it at the old minimum and $12,240 still reverts to 24.99 percent at month 19, which then drags on for roughly five more years.
The side-by-side table
The same $18,000 of debt under three scenarios, paying $560 a month throughout:
| Scenario | Time to debt-free | Total interest + fees | Cheaper than scenario 1 by |
|---|---|---|---|
| 1. Keep existing (avalanche) | about 50 months | about $9,990 | - |
| 2. Personal loan at 13%, 48mo, 3% fee, keep paying $560 | about 42 months | about $5,110 (incl. $557 fee) | about $4,880 |
| 3. Balance transfer 0% for 18mo, 4% fee, then 24.99% | about 37 months | about $2,610 (incl. $720 fee) | about $7,380 |
This is the table that matters. One pass through a debt consolidation calculator spreadsheet produces it from your actual numbers in under five minutes.
To run a single leg without a spreadsheet, plug that scenario’s balance, rate, and payment into the payoff calculator and read the months and total interest it returns. Do it once per scenario and you have the comparison by hand:
The three conditions the math leans on
Consolidation produces savings when three conditions hold at the same time:
- The new effective rate is meaningfully lower than the weighted-average current rate. A spread of around 5 percentage points or more is where consolidation typically clears the fees. Smaller spreads can work but the fees eat them.
- The monthly payment stays roughly as high as it was before consolidating. A wide enough rate cut still saves money at the lower contractual payment, but dropping the payment stretches the term and eats into the gain. On a balance transfer, coasting at the old minimum through the promo can erase it entirely.
- The fees fit inside the saved interest. A 5 percent origination fee on $18,000 is $900; the consolidation has to save at least $900 in interest to break even before delivering any net benefit.
The Debt Payoff Calculator Ultimate template re-solves the payoff the moment you change the payment you plan to make, and shows the interest that change saves against paying minimums only. That is where the second condition becomes visible: the difference between holding the payment high and letting it drop shows up in dollars instead of intuition.
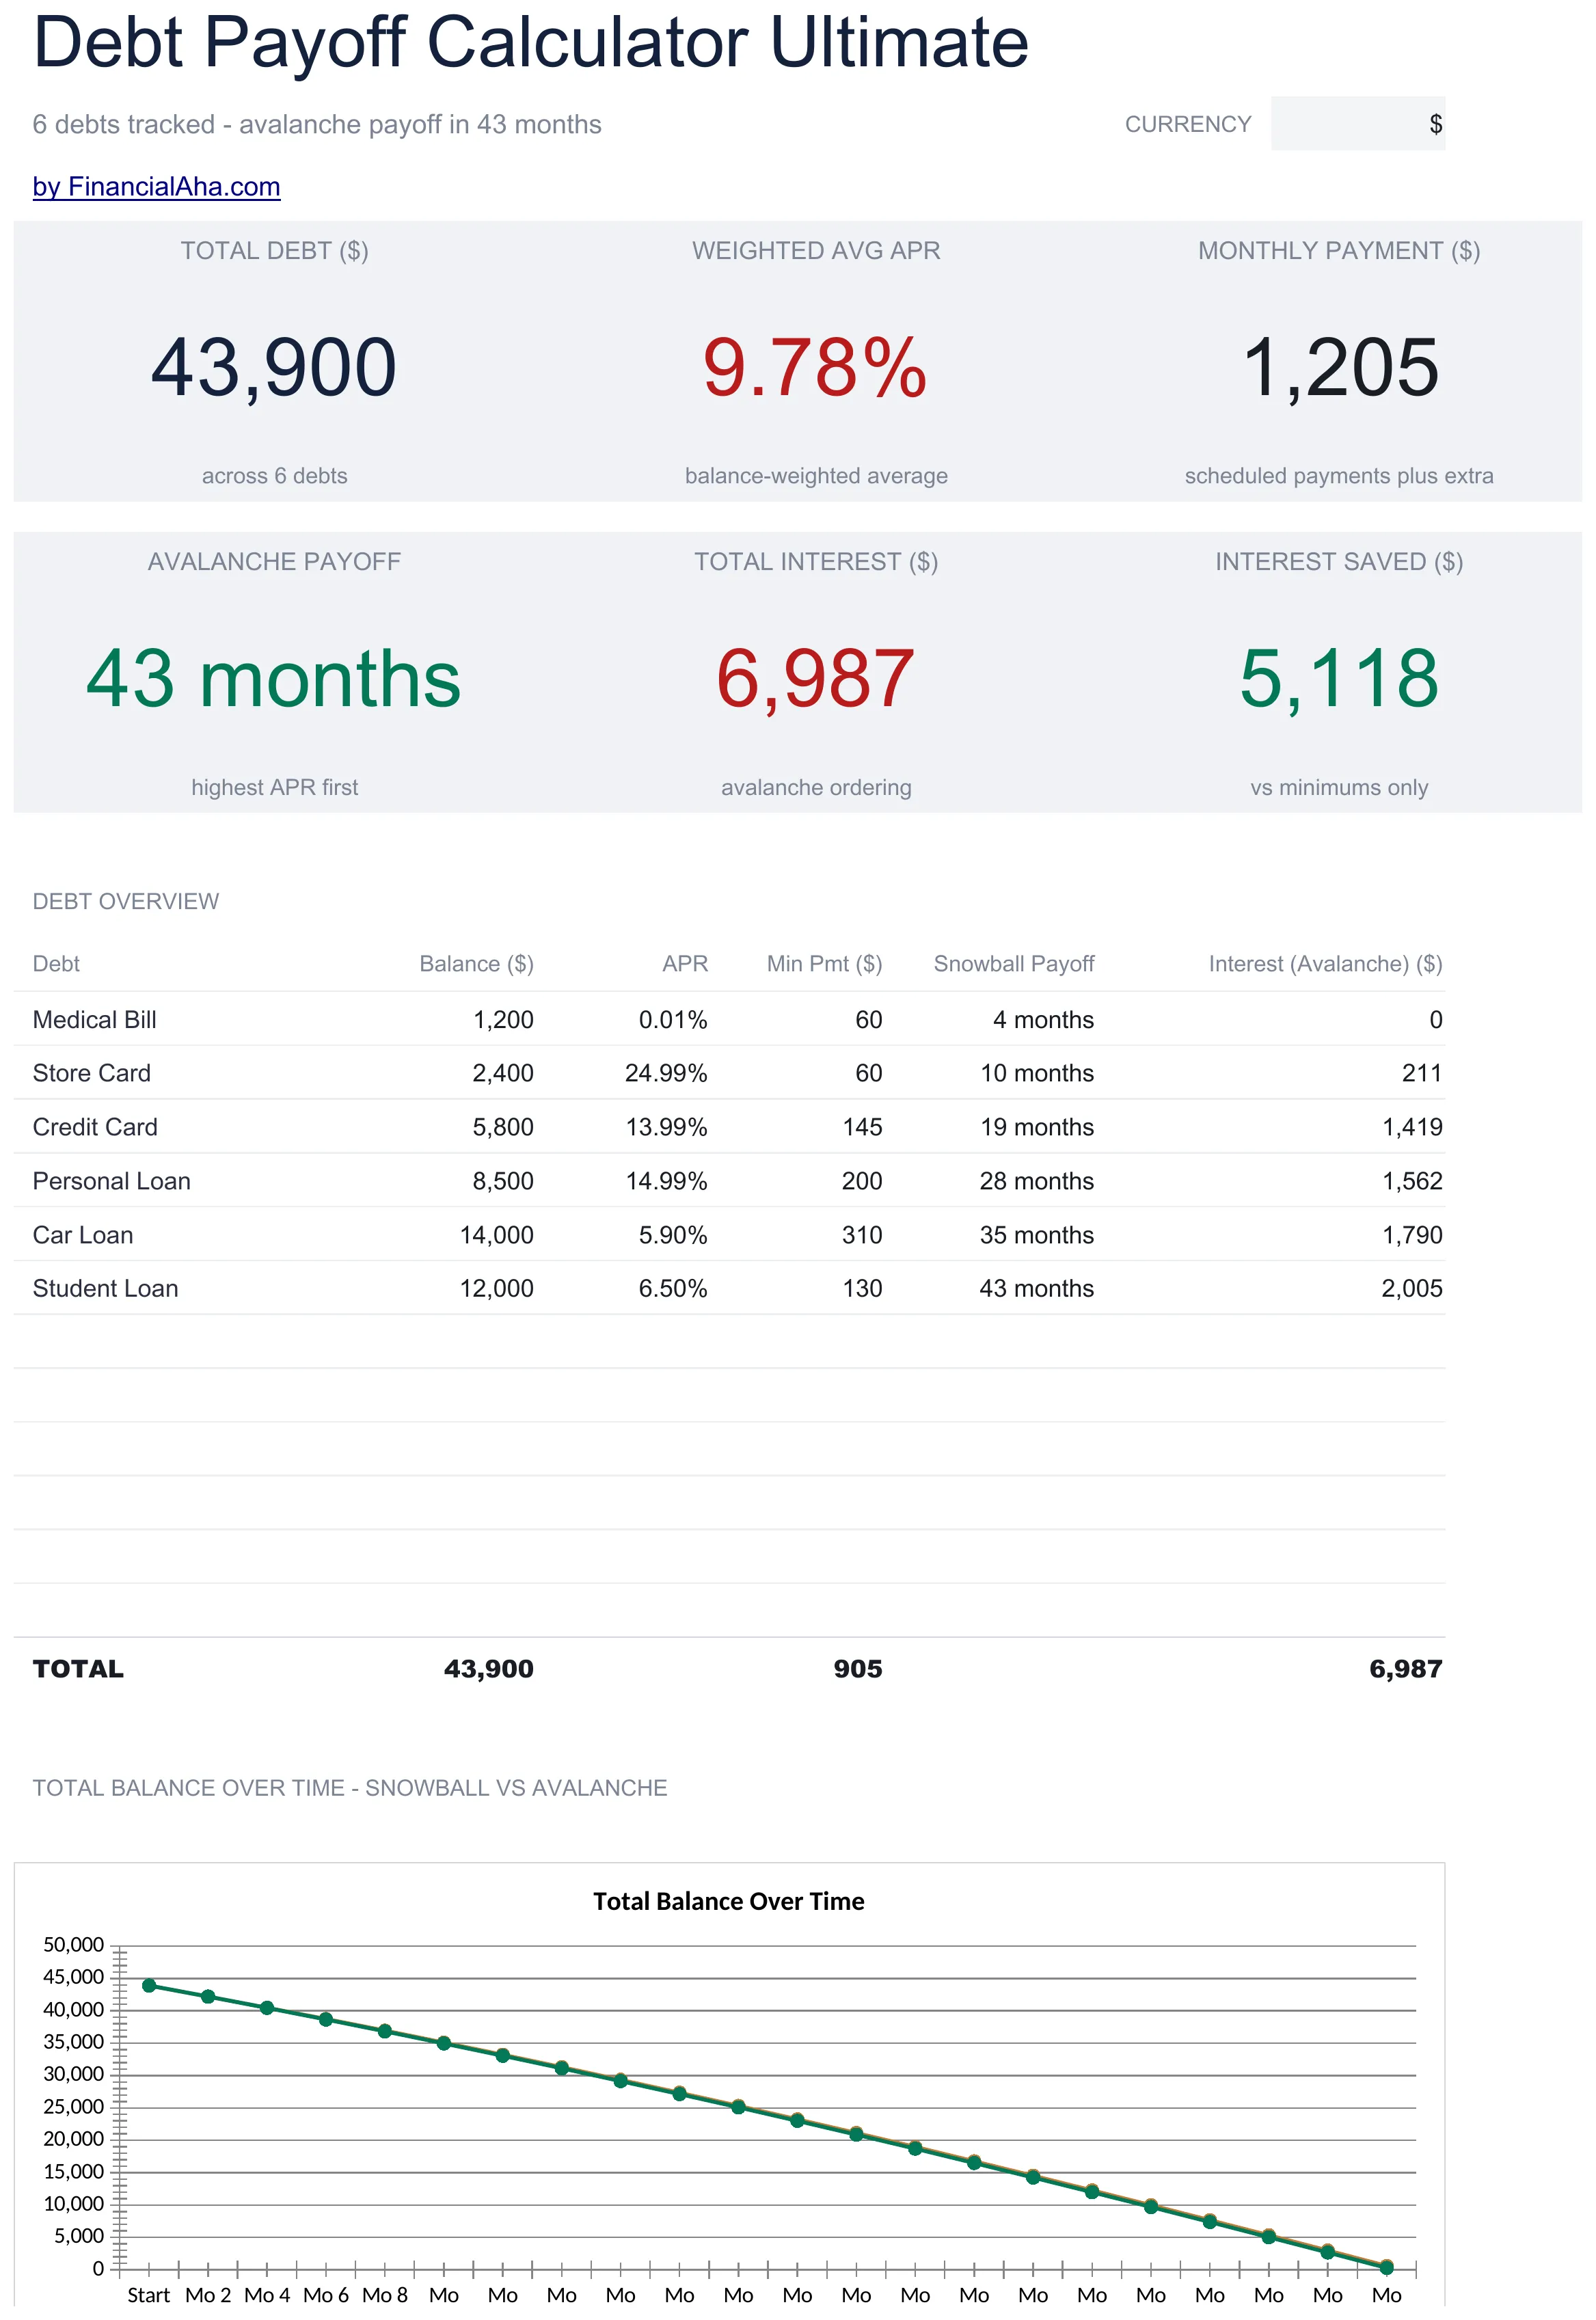 The Debt Payoff Calculator Ultimate ($29) tracks up to twelve debts with a balance-weighted average rate and compares payoff orderings. It models the “keep the cards” baseline; the personal-loan and balance-transfer legs are the ones you set up separately.
Four ways the math goes the other direction
The CFPB’s guidance on consolidating credit card debt points to several common failure modes. Four show up in the spreadsheet in dollars.
Catch 1: fees eat the spread. A 13 percent personal loan looks great until the 7 percent origination fee is amortized in. Effective rate ends up around 17 percent. The spreadsheet shows this; the lender’s offer letter doesn’t.
Catch 2: longer term, more total interest. A 60-month consolidation loan at 12 percent against 36-month credit card payoffs at 22 percent can produce more total interest paid, even though the rate is lower, because the principal sits longer. Time-weighted, not rate-weighted, is the right comparison.
Catch 3: promo period expiration. Balance transfers at 0 percent are only 0 percent for the promo window. The post-promo rate is usually 18-25 percent. If a meaningful balance remains at month 19, the savings reverse fast.
Catch 4: teaser rates with rate adjustments. Some personal loans advertise low introductory rates that step up after 12 or 24 months. Running the calculation with the post-step rate (rather than the marketing rate) shows what the loan actually costs.
The behavior question - the spreadsheet doesn’t solve it
This is the catch that no spreadsheet can model. When the cards are paid off by a consolidation loan, three credit lines suddenly have zero balances and full credit limits available. A meaningful share of consolidators run new balances back up on the freed cards over the following year or two. The result is the consolidation loan plus restored card balances - more debt than they started with.
The spreadsheet says nothing about whether someone will run the cards back up; that’s a separate question from “does the rate work.” What it can do is model both versions: cards stay at zero, and cards drift back up to half their original balance. The second scenario laid out in numbers tends to read differently than the same warning laid out in a paragraph.
Some people find it useful to close the cards immediately after consolidation, accepting the small temporary hit to credit utilization, specifically to remove the option. Others keep them open but freeze them. Either is a behavior choice. The spreadsheet stays out of it; it just runs the math.
What about home equity?
Some consolidation options use a home equity loan or HELOC to pay off unsecured debt. Rates can be lower than personal loans (often 8 to 12 percent). The CFPB’s consolidation guidance flags a specific risk here: turning unsecured credit card debt into debt secured by a house. Falling behind on credit card payments hurts credit; falling behind on a HELOC has the foreclosure risk attached.
The spreadsheet can model the rate and fee math, but it can’t model that risk. Useful to note both.
A small-balances note
For total card balances under about $4,500, the math behind consolidation tends to come out marginal. The rate-spread savings are small in absolute dollars, and the time spent shopping rates and changing autopay setups can exceed those dollars. A direct payoff approach, either the debt snowball spreadsheet for behavior momentum or the avalanche method covered in snowball vs avalanche, is one option that doesn’t require restructuring at all.
Setting it up by hand
To build a barebones version yourself:
- New Excel or Google Sheets file. Three sheets: Existing, Personal Loan, Balance Transfer.
- On Existing: list each card with balance, APR, minimum. Weighted-average APR via
=SUMPRODUCT(balances, APRs)/SUM(balances). - Use
=NPER(rate/12, -payment, balance)for months to payoff. - Total interest:
=(months * payment) - starting_balance. - Personal Loan tab: amortize the loan amount including origination fee.
=PMT(rate/12, term, -loan_amount)for the contractual payment. - Balance Transfer tab: two phases. Phase 1 (promo) puts all payment to principal at 0%. Phase 2 amortizes the remaining balance at the post-promo rate with NPER.
- A summary tab pulls the three totals together.
A few hours of careful work, and the fee and phase logic is where a hand-built version quietly goes wrong. The Debt Payoff Calculator Ultimate ($29) handles the “keep the cards” leg across up to twelve debts, with a balance-weighted average rate, three payoff orderings, and an extra-payment box that re-solves instantly. For the balance-transfer leg specifically, the Credit Card Payoff Ultimate ($29) adds a dedicated balance-transfer sheet that models the fee, promo window, and post-promo rate rather than assuming a benefit.
Templates that fit this situation
- Debt Payoff Calculator Ultimate ($29) - Up to twelve debts, a balance-weighted average rate, three payoff orderings compared (smallest balance, highest rate, custom), and an extra-payment box that re-solves instantly with the interest it saves. Models the keep-the-cards baseline in this guide.
- Credit Card Payoff Ultimate ($29) - Up to ten cards with per-card utilization, plus a dedicated balance-transfer sheet that models the fee, promo window, and post-promo rate. Fits the balance-transfer leg specifically.
- Debt Snowball Ultimate ($29) - Snowball-specific tracker with payoff milestones and rollover payments. Fits if behavior momentum matters more than rate optimization.
- Financial Planning Spreadsheet ($29) - A Google Sheet with net worth, assets, debt and month-by-month cash flow in one place, plus a projection that runs to an end year you set. Useful for seeing where the debt balances sit against the rest of the picture.
Related
- Debt Snowball Spreadsheet: Payoff Order in One Excel File - Behavior-first payoff ordering
- Debt Payoff Calculator: Snowball vs. Avalanche Compared - Strategy comparison with worked example
- Credit Card Payoff Calculator - Multi-card payoff and the balance-transfer math up close
- The 1% Rule for Debt Payoff - Small payment increases that compound
Frequently asked questions
What is debt consolidation exactly?
Combining multiple debts into one new loan with a (usually) lower rate. The math saves money only if the new rate plus fees is meaningfully lower than the weighted average rate of the original debts.
What is the difference between consolidation and balance transfer?
Consolidation typically uses a personal loan to pay off all debts; the personal loan has a fixed term and rate. Balance transfer moves credit card balances to a new card (often 0 percent for a promotional period); after the promo, the rate jumps.
What is the catch?
Three common catches: origination fees on personal loans (1 to 8 percent), balance-transfer fees on cards (3 to 5 percent), and lifestyle drift - paying off the old cards and then running them back up. The spreadsheet models the first two; the third is behavior.
What does the break-even math look like?
Two thresholds matter. First, the new effective rate (loan APR plus amortized origination fee) needs to be below the weighted-average current rate by enough margin to offset the longer term. Second, the saved interest has to exceed the fees in absolute dollars. The spreadsheet flags both.
Does consolidating debt hurt your credit score?
It can move in both directions. Opening a new loan or card adds a hard inquiry and lowers the average age of accounts, which can dip a score in the short term. Paying down card balances lowers credit utilization, which tends to help. The spreadsheet models the dollars of interest and payoff time, not the score.
Sources
- Consumer Credit - G.19 - Federal Reserve
- What do I need to know if I'm thinking about consolidating my credit card debt? - Consumer Financial Protection Bureau
About this article
Credit card and 24-month personal loan APRs checked against the Federal Reserve G.19 Consumer Credit release (Q1 2026). Payoff timelines and interest totals recomputed with standard amortization (NPER and PMT) for the $18,000 three-card example. Product claims checked on 2026-09-10 against the shipped workbooks: Debt Payoff Calculator Ultimate (Debt Setup, Strategy Comparison, What-If Analysis), Credit Card Payoff Ultimate (Card Setup, Balance Transfer, Utilization Tracker) and the Financial Planning Google Sheet (Summary, Debt, Cashflow, Projection). Last reviewed September 2026.