Hong Kong
Monthly Budget Template for Hong Kong
Track your income in HKD, manage MPF contributions, and everyday expenses - all in a Google Sheets template you own.
In Depth
A Capped Standard Rate, 5% MPF, and the Housing Cost That Overshadows Both
Hong Kong's salaries tax system caps the effective rate through the standard rate mechanism. Progressive rates of 2%, 6%, 10%, 14%, and 17% apply to net chargeable income in bands, but the standard rate on total net income applies whenever it produces a lower figure. That standard rate has been two-tiered since the 2024/25 year of assessment: 15% on the first HKD 5 million of net income and 16% above that. There is no VAT, no capital gains tax, no dividend tax, and no estate duty. This makes Hong Kong one of the lightest personal tax environments among developed economies, and it means the gap between gross and net salary is unusually narrow.
The Mandatory Provident Fund requires 5% from both employer and employee, each capped at HKD 1,500/month on maximum relevant income of HKD 30,000. For someone earning HKD 60,000/month, the mandatory MPF contribution is still just HKD 1,500 - effectively 2.5% of actual income. Tax-Deductible Voluntary Contributions (TVC) of up to HKD 60,000/year offer a way to save more while reducing salaries tax liability. The MPF balance is locked until age 65 in most cases, making it a long-term asset rather than accessible savings.
Where Hong Kong budgets come under the most pressure is housing. Since the extra residential duties were scrapped on 28 February 2024, every residential buyer faces the same stamp duty scale, which runs from a flat HKD 100 up to HKD 4 million through to 4.25% on properties above roughly HKD 21.74 million. Rent or mortgage payments frequently consume 40-50% of household income even for well-paid professionals. The result is that despite low taxes, disposable income after housing can be tighter than salary figures might suggest.
Hong Kong
Budgeting in Hong Kong: What's Different
Hong Kong's financial system features low taxes, mandatory provident fund contributions, and a high cost of living. Understanding these shapes how you approach budgeting.
Low tax rates mean more take-home pay
Hong Kong has one of the world's lowest tax regimes. Salaries tax is charged at progressive rates (2% to 17%) or at the standard rate on net income, whichever produces the lower bill. Since the 2024/25 year of assessment the standard rate has been two-tiered: 15% on the first HKD 5 million of net income and 16% on the rest. There is no sales tax, VAT, or capital gains tax. This means a larger portion of your gross salary becomes take-home pay compared to most other developed economies.
MPF contributions are mandatory but modest
The Mandatory Provident Fund requires 5% employee contribution and 5% employer contribution, each capped at HKD 1,500/month (based on maximum relevant income of HKD 30,000). For higher earners, the MPF contribution is a small percentage of total income. Budgeting from your after-MPF salary accounts for this deduction.
No capital gains tax simplifies investment tracking
Hong Kong does not impose capital gains tax, dividend tax, or estate duty. Investment returns are yours in full. For budgeting purposes, this means investment income doesn't create a separate tax complication - a simpler picture than many other financial centres.
Housing dominates Hong Kong budgets
Hong Kong is consistently ranked among the most expensive housing markets globally. Rent often consumes 30-50% of income, even for well-paid professionals. Whether renting or paying a mortgage, housing is typically the single largest budget category by a wide margin. Tracking this alongside other expenses helps see the full cost-of-living picture.
Property stamp duty adds significant purchase costs
Hong Kong levies Ad Valorem Stamp Duty (AVD) on property purchases. The extra residential duties (Special Stamp Duty, Buyer's Stamp Duty and New Residential Stamp Duty) were removed on 28 February 2024, so one scale now applies to all residential buyers. Under the scale in force from 26 February 2026, a flat HKD 100 applies up to HKD 4 million, rates step up through 1.5%, 2.25%, 3% and 3.75%, reach 4.25% between roughly HKD 21.74 million and HKD 100 million, and top out at 6.5% for the highest-value properties, as set out in the GovHK stamp duty rate table. Above the entry band this is still a substantial upfront cost on top of high property prices.
Get the Template
Getting Started
Configuring the Budget Template for Hong Kong
Switch the currency to HKD
There's a currency picker at the top of the dashboard - switch it to HKD. The calculations stay the same - only the display changes.
Enter your after-MPF salary
Use the amount actually credited to your bank account after the 5% MPF employee contribution. Your payslip shows the net amount. If you have other income (bonuses, investments), add those as separate lines.
Customize expense categories for Hong Kong
Add categories for rent or mortgage, management fees, utilities (CLP/HK Electric, Towngas, water), mobile and broadband, MTR/transport, groceries, dining out (a significant category for many Hong Kong residents), helper salary (if applicable), and insurance premiums.
Add a line for the annual tax payment
Hong Kong assesses salaries tax annually, with demand notes generally issued between January and April. Tax is not withheld from monthly pay as it is in many countries, so the bill arrives as a lump sum. Some people give it its own monthly line in the budget. The IRD assessment includes a provisional tax figure for the following year, which gives a starting estimate.
Plan for Hong Kong-specific expenses
Account for annual expenses like rates and government rent (billed quarterly), tax payments, insurance renewals, and travel. Some expenses are seasonal - higher electricity in summer due to air conditioning, and potentially higher spending during Chinese New Year and holiday periods.
See It In Action
What the template looks like
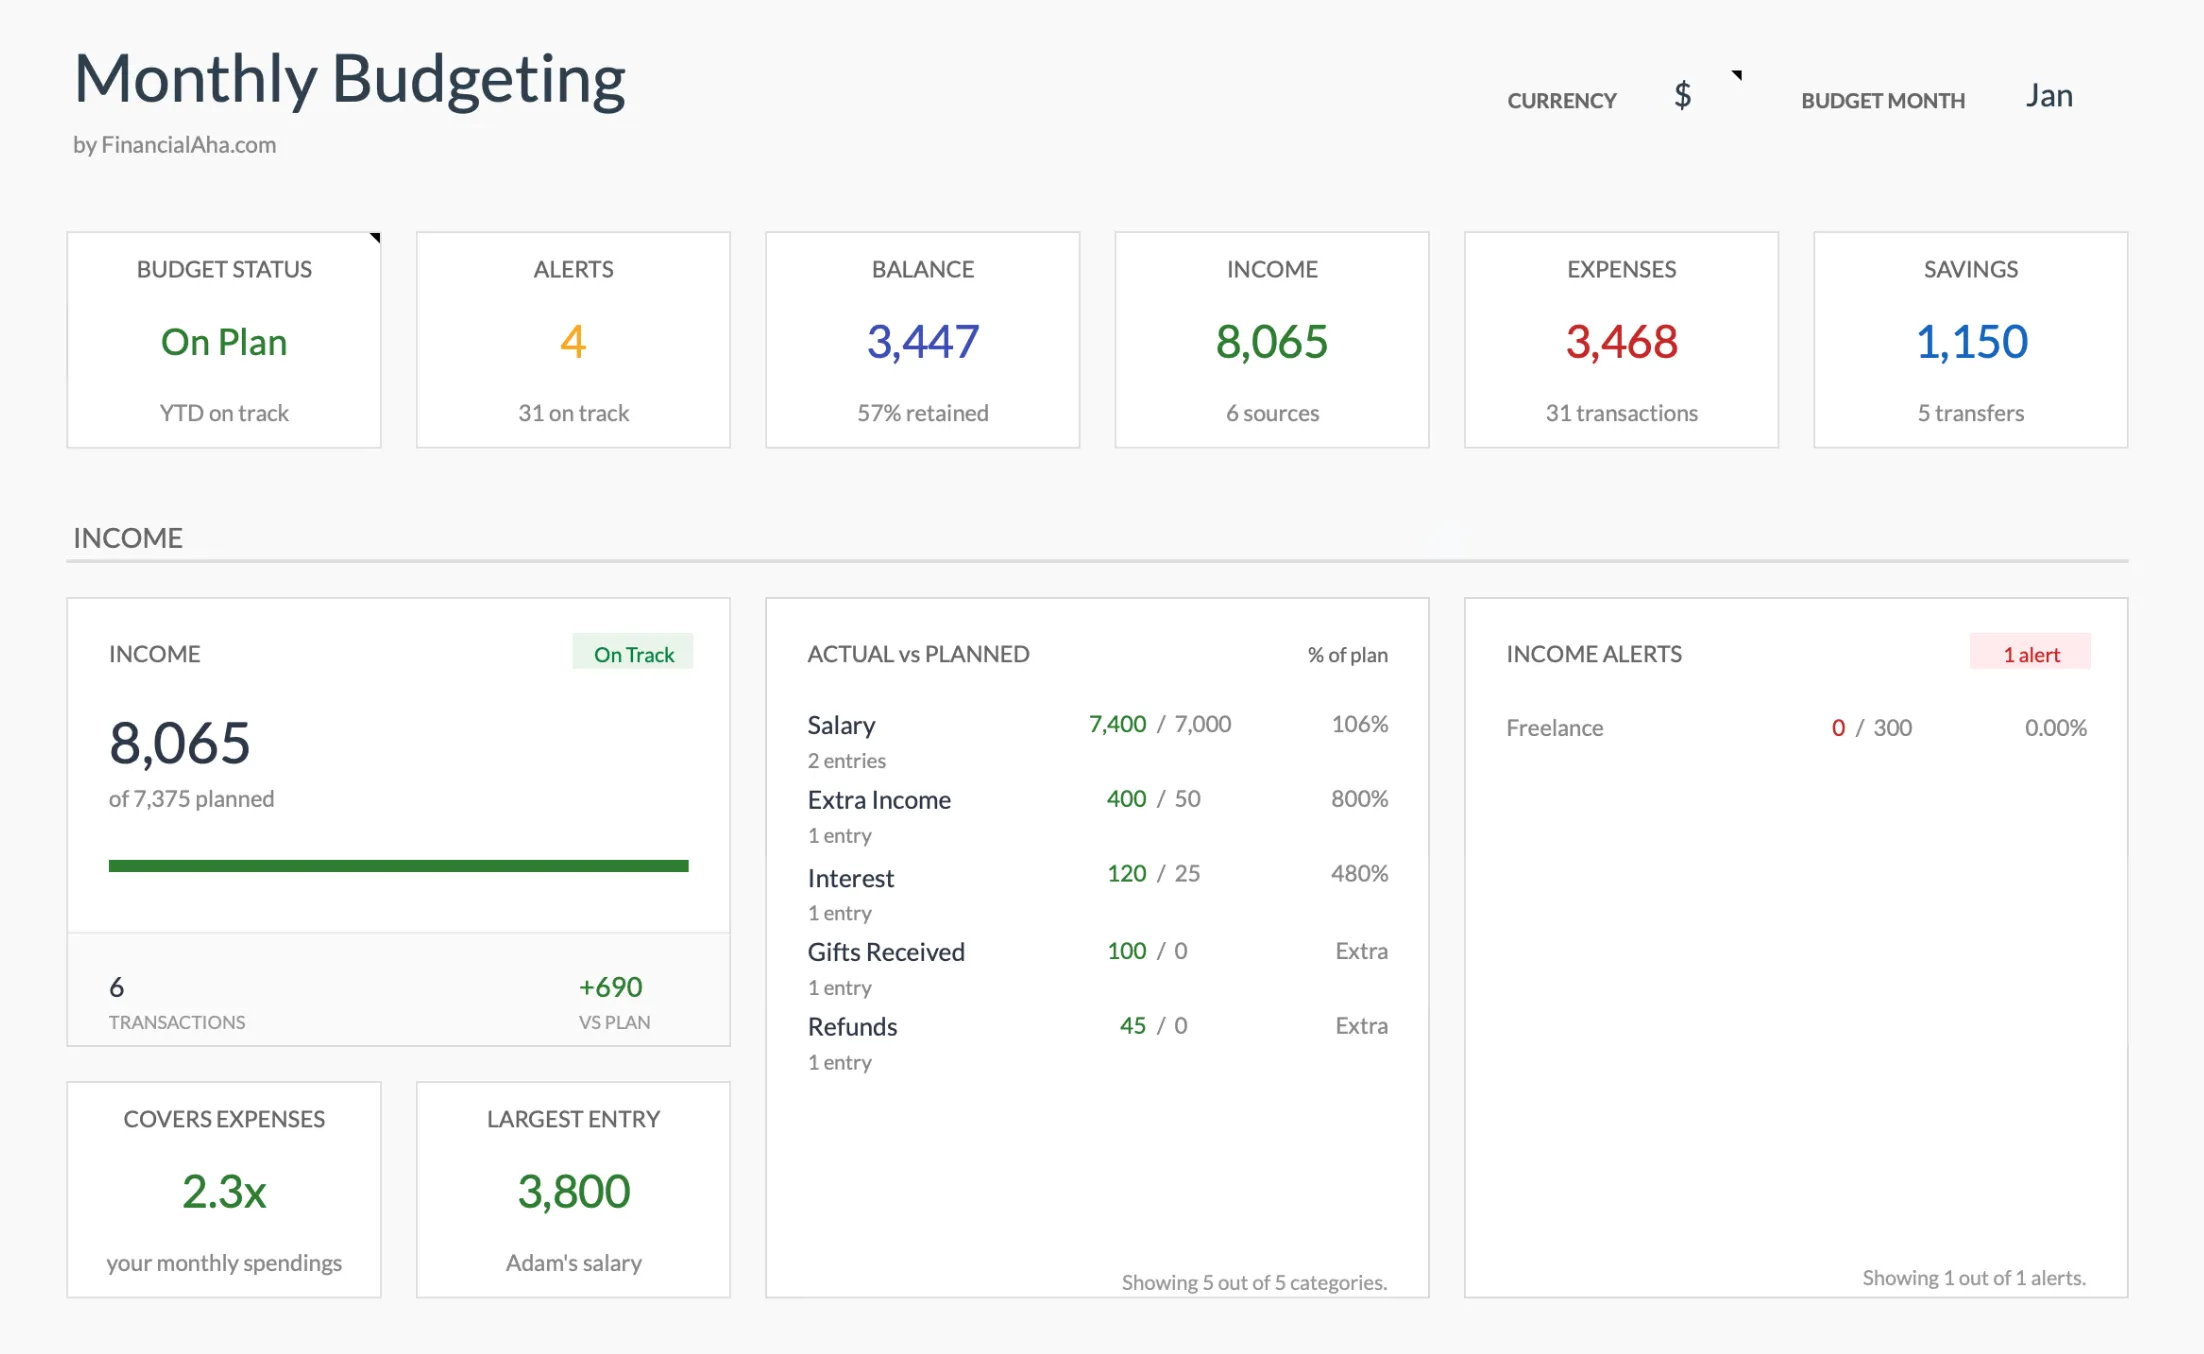
Browse through the template to see the dashboard, the entry sheets, and the summaries it produces, all adaptable to your local financial setup.
- Built-in currency selector
- Calculations update automatically
- Visual summaries of your numbers
- No setup required
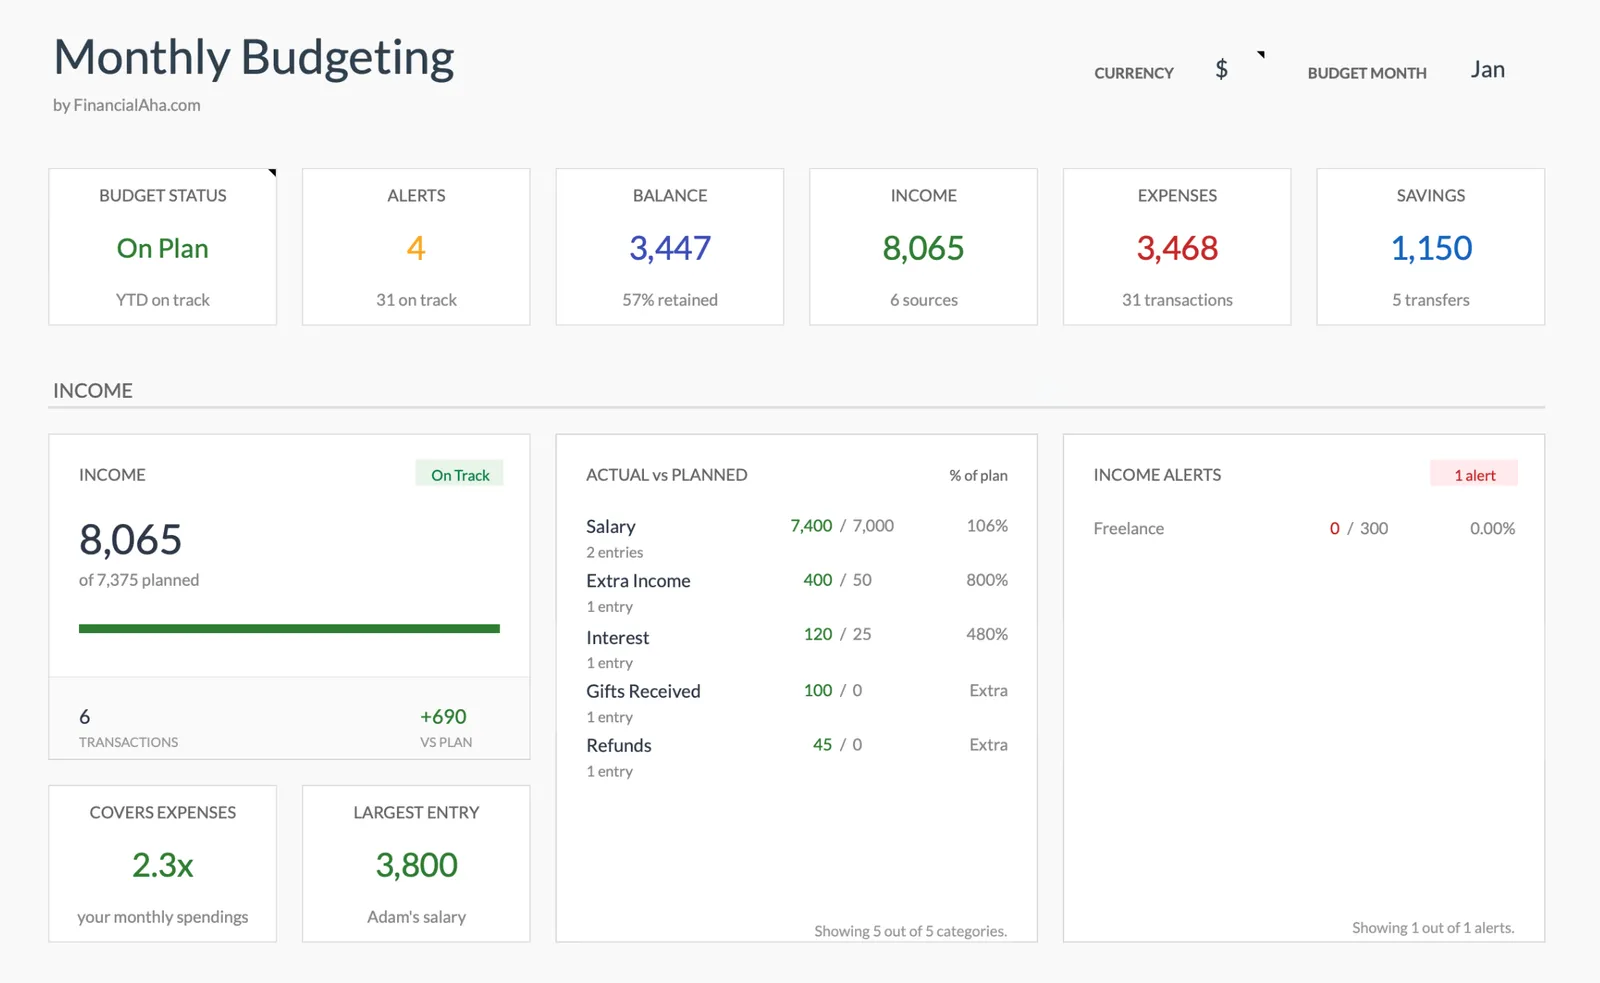
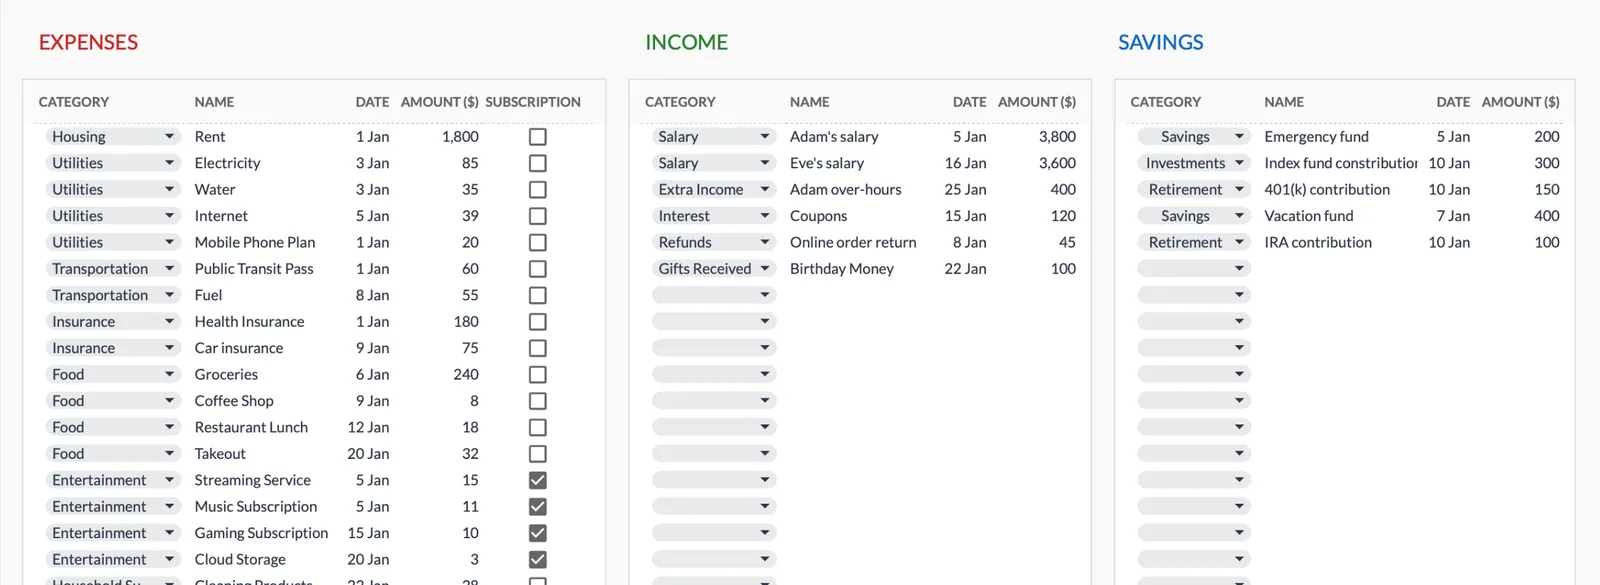
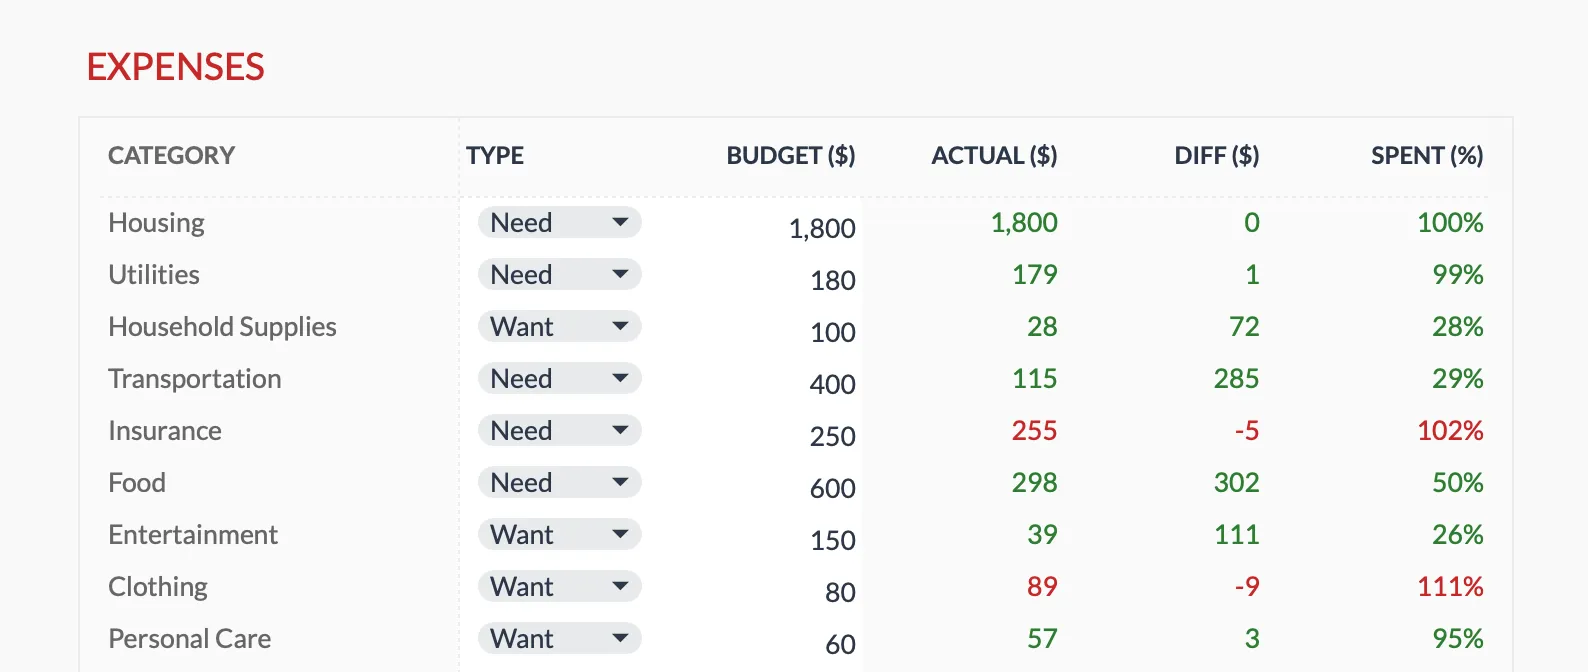
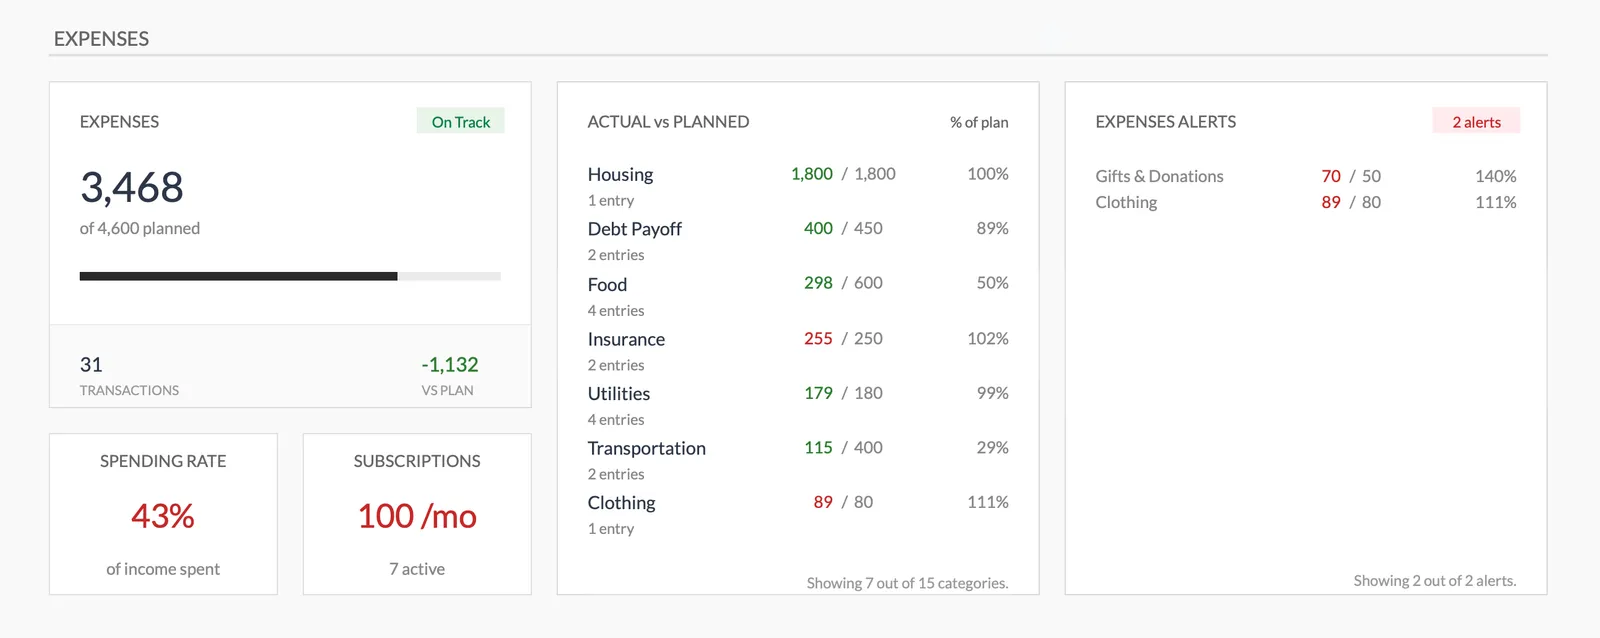
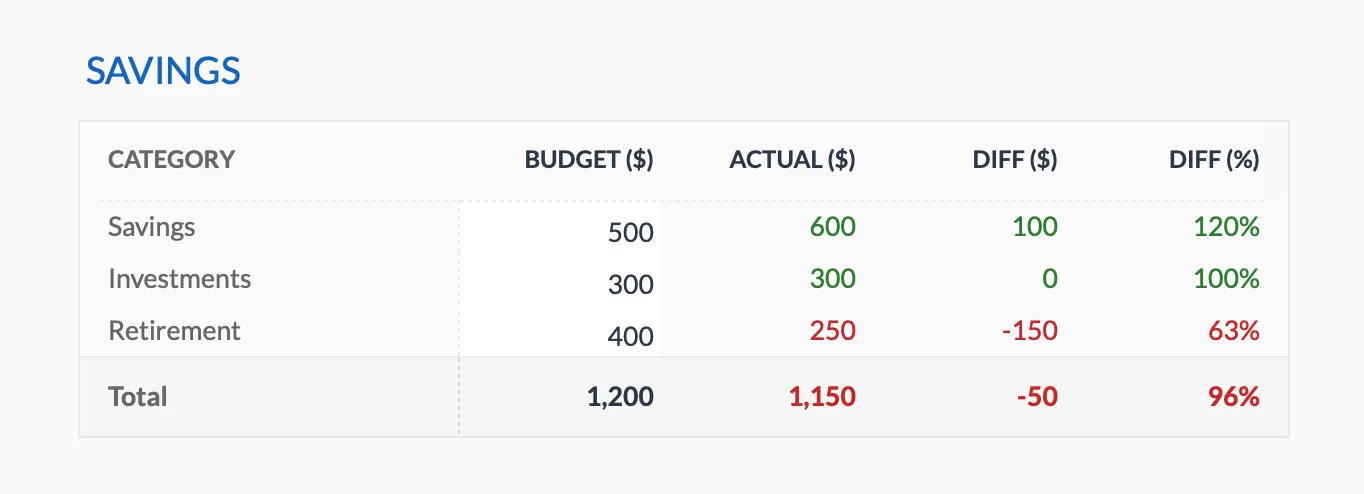
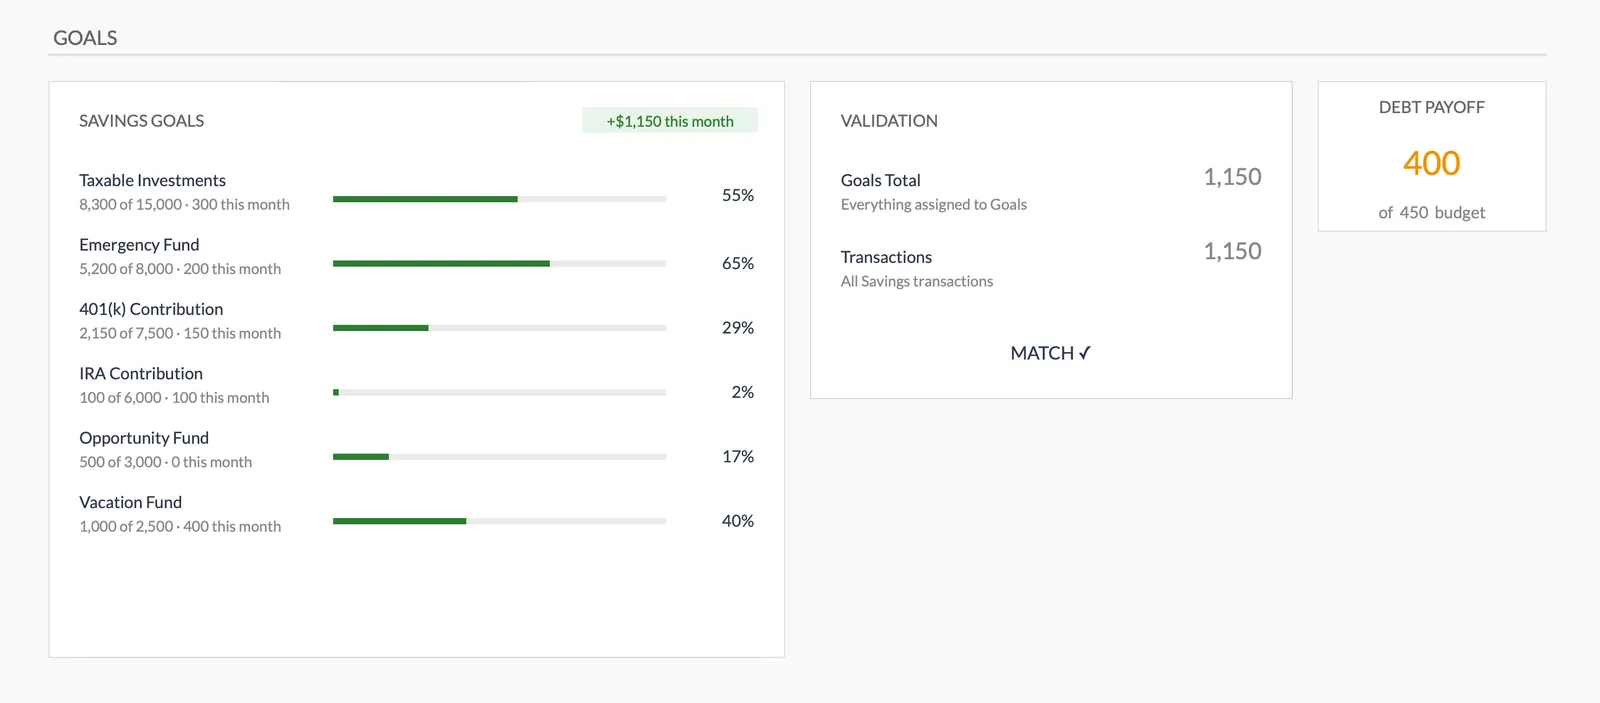
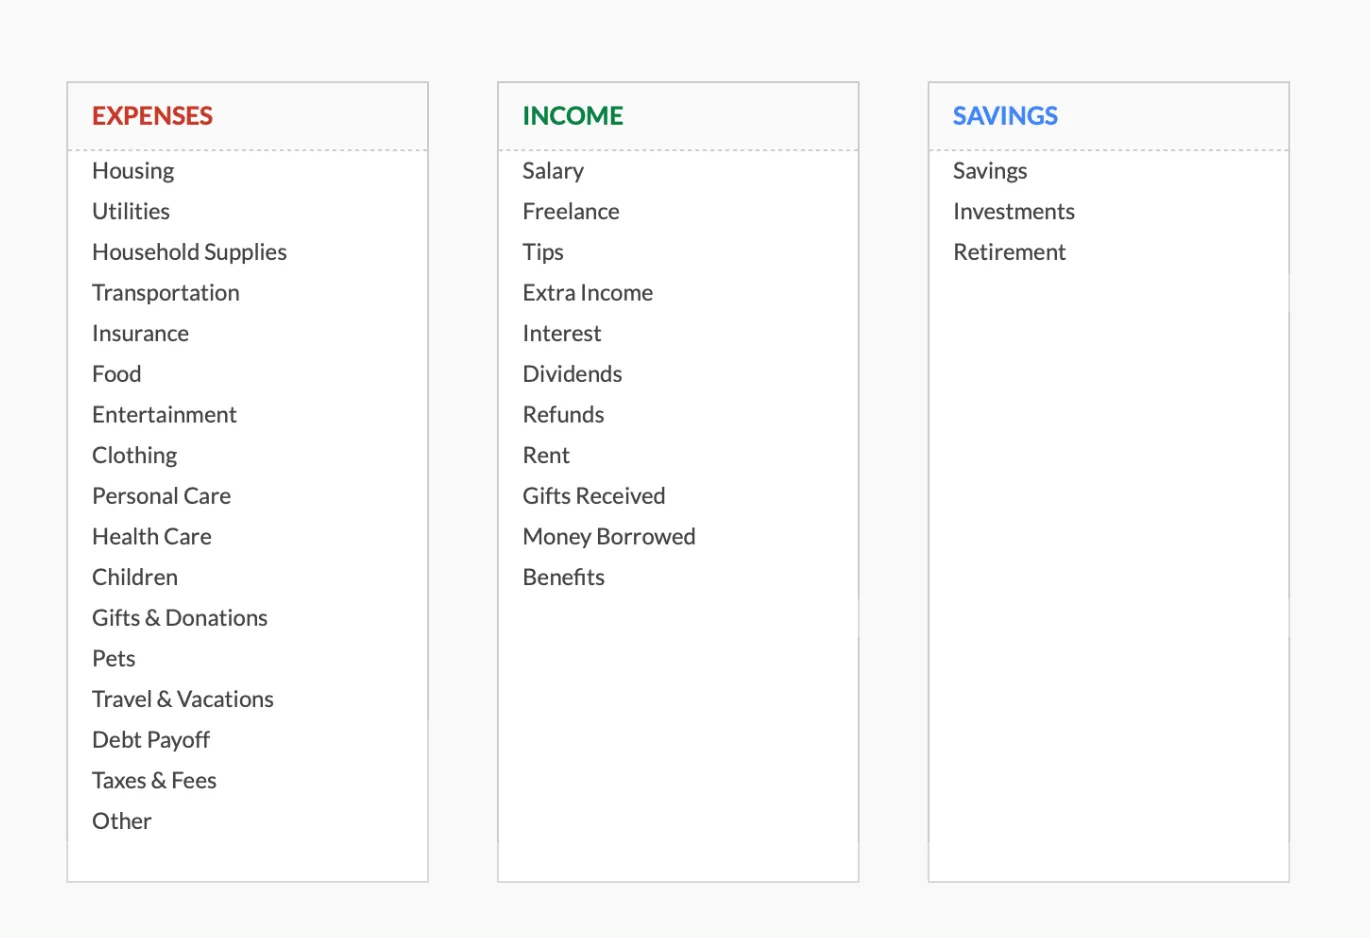
Dashboard with income, expenses, and savings at a glance
Log transactions with automatic categorization
Set targets per category and track actual spending
Visual breakdown of where your money goes
Track savings goals alongside your budget
Monitor progress toward financial goals
Fully customizable expense, income, and savings categories
Common Questions
Monthly Budget Template for Hong Kong - FAQ
Does this template use Hong Kong dollars?
Yes - select HKD from the currency dropdown in the header. The math applies in any currency, so the formulas don't change.
Should I track MPF in my budget?
MPF employee contributions (5% capped at HKD 1,500/month) are deducted before your take-home pay. Just use your net salary as income. If you make voluntary MPF contributions (TVC), track those as a budget category since they come from your disposable income.
How do I budget for annual tax payments?
One approach is to estimate the annual salaries tax using the IRD tax calculator or last year's assessment, divide by 12, and carry that as a monthly line. Hong Kong splits the bill into two instalments, with the first generally due in January and the second in April.
Can I track helper salary and expenses?
Yes. If you employ a domestic helper, add their salary, food allowance, insurance, and visa-related costs as budget categories. These are significant monthly expenses for many Hong Kong households.
Is there a Hong Kong-specific version?
The template is the same worldwide - designed to be customizable. This page explains how to adapt it for Hong Kong finances. You can rename categories and set everything up to match your specific situation.
How does this compare to Hong Kong banking apps like ZA Bank or Mox?
Banking apps offer automated spending tracking for transactions within their ecosystem. This template covers all spending regardless of payment method, offers more customization, and keeps data in your own Google Drive. Manual entry requires more effort but provides a more complete view.
Can't find the answer you're looking for? Contact our team
Ready to get started?
Download instantly and start managing your finances, or contact us to design a custom template package for your needs.
Tax rules, rates, and contribution limits change, and official publications can themselves lag behind the law in force. We review these figures on a best-effort basis against sources we consider authoritative, but we cannot guarantee they are current, complete, or that better sources do not exist, and nothing here is tax, legal, or financial advice. For decisions, the relevant government authority is the reference.