A year-end budget review walks back through the 12 months you just lived: plan-vs-actual variance per category, your savings rate month by month, the irregular expenses that caught you off guard, your net worth change, and a checklist of fixes for next year's plan. Run it in November or December for the calendar year, or mid-year on a rolling 12 months, since the exercise is identical either way. Our Annual Budget Template holds Plan and Actual columns for every category across all 12 months, and its Summary tab turns them into variance against plan, a savings rate and the best and worst months of the year.
I’m publishing this in May because the most useful budget review isn’t actually December. A mid-year review catches problems early and leaves 7 months to course-correct. The exercise is identical; only the timing differs, and the same steps line up with the annual budget review checklist if you prefer a shorter run-through.
This post walks through the five sections of a complete budget review, with a worked example and the spreadsheet structure that supports it.
Why review at all
Three reasons.
You can’t plan next year without knowing this year. A budget for 2027 built without looking at 2026 actuals is mostly guessing. The review converts the past 12 months from “stuff that happened” into “data that informs.”
Surprises become categories. The thing that blew your budget twice in 2026 (medical, car repair, family event) deserves its own line in 2027 instead of disappearing into “miscellaneous.”
Habits become visible. Drift in dining spending, growing subscription totals, the slow creep of a category that started small. The annual view shows trends a monthly view hides.
The review takes about 90 minutes to do well. Lighter versions take 30 minutes. Both are worth it.
Section 1: monthly variance per category
The headline section. For each category, compare planned (what you budgeted) vs actual (what you spent) for each of the 12 months.
| Category | Plan | Actual | Variance | Variance % |
|---|---|---|---|---|
| Housing | 2,400/mo | 2,400/mo avg | 0 | 0% |
| Groceries | 950/mo | 1,080/mo avg | +130/mo | +14% |
| Dining | 280/mo | 410/mo avg | +130/mo | +46% |
| Transportation | 240/mo | 220/mo avg | -20/mo | -8% |
| Entertainment | 150/mo | 95/mo avg | -55/mo | -37% |
| Subscriptions | 95/mo | 145/mo avg | +50/mo | +53% |
| Personal care | 110/mo | 80/mo avg | -30/mo | -27% |
| Travel | 250/mo | 380/mo avg | +130/mo | +52% |
Categories with the largest variance get the attention. Above, four categories were significantly over (groceries, dining, subscriptions, travel) and three were under. Net: roughly $300 a month over plan.
The interesting question isn’t “why was dining over by 46 percent” in isolation. It’s “what changed?” Did dining go up because life changed (new restaurant nearby, social activity uptick), because the plan was unrealistic from the start, or because tracking discipline slipped?
Each variance has a different remedy. Pattern recognition matters more than aggregate numbers.
Section 2: irregular expenses that surprised you
A row per surprise. The point is to convert one-time annoyances into next-year line items.
Examples from a typical year:
| Surprise | Cost | When | What to do next year |
|---|---|---|---|
| HVAC repair | 1,400 | March | Add Home Maintenance reserve at $150/mo |
| Vet emergency | 850 | June | Add Pet emergency line at $50/mo |
| Wedding gift season | 1,200 | Summer | Plan Gifts category at $400/mo for May-Aug |
| Car battery and tires | 600 | November | Add Vehicle Maintenance reserve at $75/mo |
| Surprise medical | 700 | September | Increase HSA contribution by $1,000/yr |
Total surprises: $4,750. None of these were truly unpredictable. Each is a category that should have existed in the plan and didn’t. Next year’s plan adds the lines, sized for what you now know.
This single section often saves more in next year’s stress than the rest of the review combined.
Section 3: savings rate trend
Plot savings rate by month. Look for direction.
| Month | Income | Saved | Rate |
|---|---|---|---|
| Jan | 9,200 | 1,840 | 20% |
| Feb | 9,200 | 1,950 | 21% |
| Mar | 12,100 (extra paycheck) | 3,200 | 26% |
| Apr | 9,200 | 1,840 | 20% |
| May | 9,200 | 1,500 | 16% |
| Jun | 9,200 | 1,200 | 13% |
| Jul | 9,200 | 1,400 | 15% |
| Aug | 9,200 | 1,000 | 11% |
| Sep | 9,200 | 1,600 | 17% |
| Oct | 9,200 | 1,800 | 20% |
| Nov | 9,200 | 1,650 | 18% |
| Dec | 21,200 (bonus) | 6,400 | 30% |
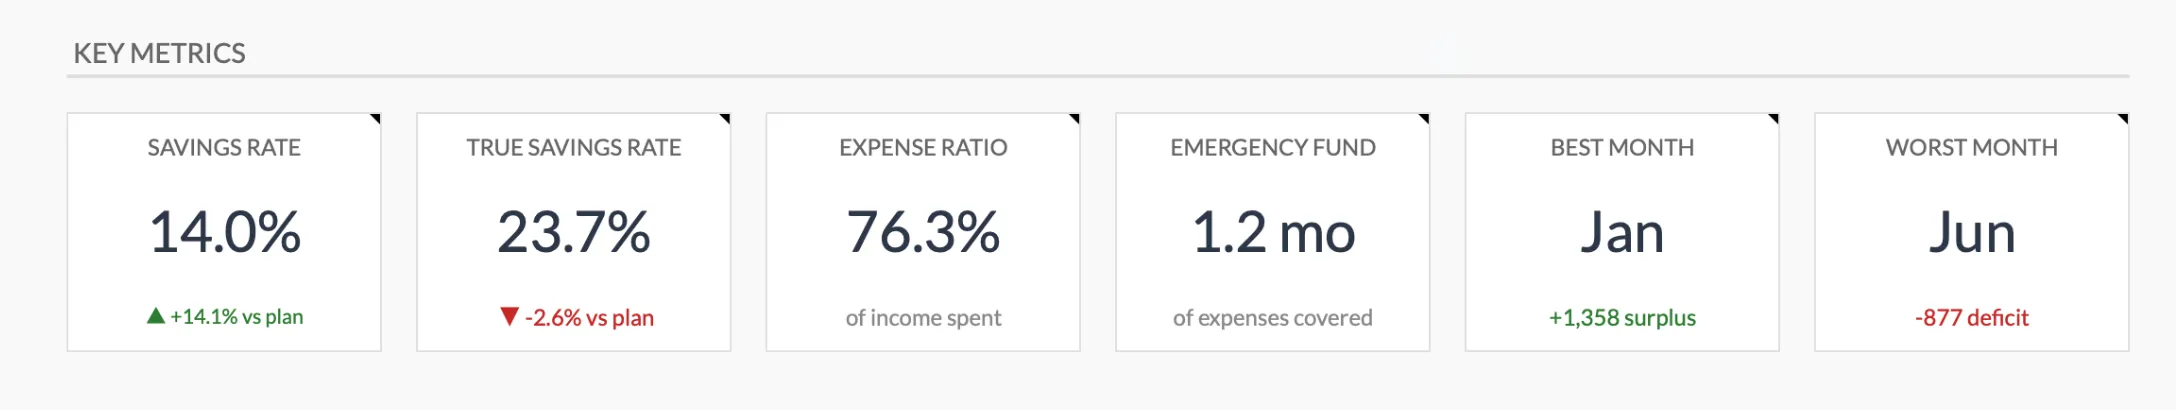
The Annual Budget Template (Premium) rolls the year into a Key Metrics panel: savings rate and true savings rate against plan, expense ratio, emergency fund cover, and the best and worst months by surplus. It reports the year as a whole rather than the month-by-month table above.
Average: around 19 percent. But the trend within the year shows a sag from May through August (summer travel and irregular expenses) and a recovery in fall. The bonus saved most of December.
The interesting work: was the summer sag a planned absorption (you knew travel would lower the rate), or did the rate slip without being noticed? Different answers, different remedies.
Section 4: net worth change for the year
A single number with context. If you have never pulled this figure together, the mechanics of adding up assets and subtracting liabilities are covered in how to calculate net worth.
Net worth, year-over-year:
- January 1: $245,000
- December 31 (or current): $293,500
- Change: +$48,500 (+19.8 percent)
Composition of the change:
- Savings contributions: $32,000
- Investment growth: $14,500
- Real estate appreciation: $5,000
- Debt principal reduction: $3,000
- Less: depreciation on vehicles: -$2,000
- Less: spending from savings (one-time withdrawals): -$4,000
Total: $48,500.
This decomposition tells you whether the net worth growth was driven by saving (great), market returns (good but not under your control), or one-time events (note for next year). The first two are repeatable; the third may not be.
Section 5: next year’s checklist
The output of the review. A concrete list of changes to make in next year’s plan.
Examples from the analysis above:
- Add Home Maintenance reserve at $150/mo (was missing).
- Add Pet emergency reserve at $50/mo (was missing).
- Increase Gifts category to $400/mo for May-Aug (was flat $150/mo).
- Add Vehicle Maintenance reserve at $75/mo (was lumped in transportation).
- Audit subscriptions category: where did the extra $50/mo come from?
- Recalibrate dining target: $280/mo was unrealistic; try $375/mo as a more honest number.
- Plan summer savings rate at 12 to 14 percent (acknowledge the seasonal pattern) instead of pretending it’ll be 20 percent.
Each item is specific and actionable. The new plan starts with these changes incorporated.
How to run the review
Three steps if you have an annual budget already in place.
- Pull actuals for each month from your transaction log into the Plan vs Actual columns of the annual budget.
- Calculate variance per category per month.
- Walk through Sections 1 to 5 above.
If you don’t have an annual budget, the review is a precondition for building one. Use bank statements and credit card downloads to reconstruct monthly spending by category, then run the same analysis. The output feeds straight into next year’s plan, which is the subject of how to plan a yearly budget in Google Sheets.
In the Annual Budget Template, steps 1 and 2 live on the Annual Plan tab, which holds Plan and Actual columns for every category in each of the 12 months and computes the difference in currency and percent alongside a monthly average and a year-to-date total. Step 3 stays reading work, though the Summary tab collects the savings rate, the expense ratio and the categories that ran over plan.
Common mistakes
Reviewing only the bad categories. The categories where you came in under plan also matter. Were you genuinely frugal there, or did you just not engage that part of life this year? A category at $0 spend isn’t always a win.
Treating one bad month as a trend. A single $700 medical month doesn’t mean you need a $700/mo medical line. Look for patterns across multiple months.
Skipping the savings rate decomposition. The headline savings rate hides whether you saved consistently or whether the year was rescued by one bonus. The two suggest very different next-year strategies.
Not capturing the surprises. This is the single most valuable section, and the easiest to skip. Take the time.
Treating the review as a self-evaluation. It isn’t a performance review. Beating yourself up over the dining spend doesn’t change next year. Logging the pattern and adjusting the plan does.
When mid-year vs year-end review
Year-end (December): Best for capturing the full calendar year and feeding directly into January’s new plan. Most aligned with tax-year boundaries.
Mid-year (May or June): Best for course-correcting before patterns harden. Catches drifts early. The categories you’ve been over on for 5 months are more visible than at year-end after 11.
Quarterly (March, June, September, December): Best for people who want continuous tuning. More time investment but smaller changes per cycle.
Most people benefit from at least one mid-year and one year-end. Quarterly is overkill unless your situation changes often.
Where to run your review
The fastest next step is to open a 12-month grid, drop in your actuals, and let the metrics fall out. Any of these fit the review:
- Annual Budget Template - 12-month Plan and Actual grid for every category, with monthly averages and year-to-date totals, plus a Summary tab carrying Key Metrics, over-budget alerts and charts.
- Monthly Budget Template - Planned-vs-actual monthly budget with a dashboard and category targets, if you want to reconstruct the year one month at a time.
- Budgeting Bundle - Annual, Monthly, and Travel budget templates bundled.
Once the numbers are in front of you, the annual budget review checklist turns them into the specific line items that go into next year’s plan.
Related
- Annual Budget Review Checklist
- Q3 2026 Financial Review Checklist - The autumn checkpoint that catches what is still fixable before year-end
- How to Plan a Yearly Budget in Google Sheets
- How to Calculate Net Worth
- One Page Financial Plan Template: 7 Sections That Actually Matter
- Quarterly Estimated Tax Spreadsheet
Frequently asked questions
How long does the review actually take?
About 90 minutes for a thorough version (all 5 sections, with notes). 30 minutes for a faster version (variance + surprises only). Both are useful; depth matches situation.
Should I review even if I didn't budget the year?
Yes. The exercise is more useful when you have a plan to compare against, but reconstructing the year from bank statements is itself the planning input for next year. First-time reviewers often have the biggest insights.
What if I share finances with a partner?
Run the review together. The conversations are more valuable than the numbers. Disagreements about what counts as "surprise" vs "should have planned for" are typical and worth having.
Should the review include investment performance?
Lightly. Investment performance over a single year is mostly noise; multi-year performance is more meaningful. Noting your portfolio change for the year is useful, but a single year's return tells you little on its own.
Can I run a review on someone else's finances if I'm a financial advisor?
The structure works the same way. The conversations about why things happened are richer because the client has the context you don't. Use the spreadsheet as a discussion frame, not a verdict.
How do I handle a year when my income changed a lot?
Variance percentages get noisy when income swings, so a raise or a job change mid-year is worth flagging as context next to the numbers. Some people find it clearer to review the months before and after the change as two separate stretches rather than one 12-month average, then plan next year against the current income level.
Is a year-end budget review the same as doing my taxes?
No. Taxes are about what you owe on income the government cares about; a budget review is about where your money actually went and what to change next year. They overlap on timing and on some numbers, such as HSA or retirement contributions, but the review covers spending categories and savings rate that a tax return never touches.
About this article
Template sheets, inputs and outputs checked on 2026-09-10 against the shipped Annual Budget Template Google Sheet (Summary, Annual Plan, Annual Financial Goals, Categories, Setup, Instructions tabs). All dollar amounts in the tables are illustrative worked examples, not survey figures. Last reviewed September 2026.