An annual budget review compares budgeted to actual across every category, then rolls the findings into next year's plan. Work through nine areas in order: spending, income, debt, savings, net worth, retirement, insurance, taxes, and goals. Late December or early January is the usual timing, closing out one year while shaping the next.
An annual budget review examines what worked, what didn’t, and what needs to change - turning 12 months of data into actionable plans for the year ahead.
Review tools: The Annual Budgeting Planner and Net Worth Tracker provide the structure.
Spending Analysis
Compare budget to actual for each category:
| Category | Budgeted | Actual | Variance |
|---|---|---|---|
| Housing | $18,000 | $18,000 | $0 |
| Food | $7,200 | $8,100 | +$900 |
| Transportation | $4,800 | $4,200 | -$600 |
Look for patterns: which categories consistently exceeded budget? Which had surplus? Any seasonal spikes or unexpected categories?
Key Metrics
Savings rate:
(Total Income - Total Spending) / Total IncomeHousing cost percentage:
Total Housing / Total IncomeDebt payment percentage:
Total Debt Payments / Total IncomePercentages help compare year over year even if dollar amounts change.
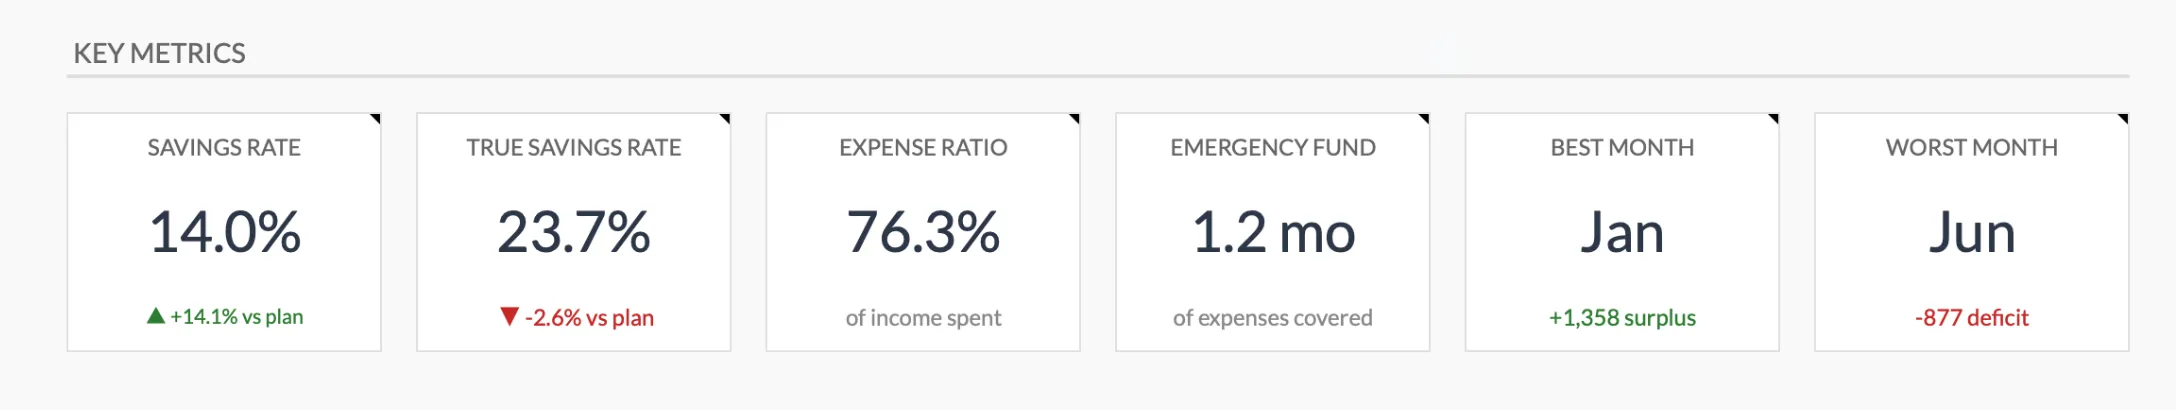 The Annual Budgeting Planner (Premium) works out its own key metrics from the plan and actual figures entered on the Annual Plan grid: savings rate, true savings rate, expense ratio, months of expenses covered, and the best and worst month of the year. Housing and debt percentages are not among them.
Income Review
Total all sources: primary employment, side income, investment income, other. Compare to previous year - did income increase, decrease, or stay flat? Assess stability for next year’s planning.
Debt Assessment
| Debt | Jan Balance | Dec Balance | Change |
|---|---|---|---|
| Credit Card | $5,000 | $2,500 | -$2,500 |
| Car Loan | $12,000 | $8,500 | -$3,500 |
| Student Loans | $25,000 | $22,000 | -$3,000 |
Calculate total debt paid down, interest paid, and remaining balance. Worth asking: is the current payoff strategy working? Any refinancing opportunities?
Savings and Emergency Fund
| Goal | Target | Current | Status |
|---|---|---|---|
| Emergency | $15,000 | $12,000 | 80% |
| Vacation | $3,000 | $3,000 | Complete |
| Car Fund | $10,000 | $4,000 | 40% |
Review whether contribution amounts were met and whether targets still make sense given life changes.
Net Worth: Year-Over-Year
| Category | Last Year | This Year | Change |
|---|---|---|---|
| Assets | $150,000 | $185,000 | +$35,000 |
| Liabilities | $80,000 | $70,000 | -$10,000 |
| Net Worth | $70,000 | $115,000 | +$45,000 |
Net worth shows the actual result of all financial activity combined. If you want to itemize assets and liabilities before comparing, the net worth statement checklist walks through what to include.
Retirement Review
The Financial Planning Template carries assets and debt forward to a chosen end year using six assumptions: income, expenses, asset growth, asset yield, debt change and inflation. Retirement accounts sit in its Assets tab as long-term savings, so the projection moves their balances rather than tracking contributions against a cap. Check your contributions against the current caps: for 2026 the 401(k) employee deferral limit is $24,500 and the IRA limit is $7,500, both up from 2025.
| Account | 2026 Limit | Your Contribution | Utilized |
|---|---|---|---|
| 401(k) | $24,500 | $15,000 | 61% |
| IRA | $7,500 | $7,500 | 100% |
Insurance Review
Review each policy (health, auto, home/renters, life, disability):
- Are coverage amounts still adequate given life changes?
- Can premiums be reduced?
Beneficiary check: Verify beneficiaries on life insurance, retirement accounts, and bank accounts. Outdated designations can override wills.
Tax Planning
Review this year: total taxes paid, effective rate, deductions used, credits claimed.
Plan for next year: adjust withholding if needed, plan tax-advantaged contributions, quarterly estimate adjustments if self-employed.
Worth considering before year-end if timing allows: maxing tax-advantaged accounts, tax-loss harvesting, charitable contributions. Pairing the review with tax season budget prep keeps documents and deductions organized before filing.
Goal Assessment
| Goal | Target | Result | Status |
|---|---|---|---|
| Build emergency fund | $12,000 | $12,000 | Achieved |
| Pay off credit card | $5,000 | $2,500 paid | Partial |
| Max IRA | $7,500 | $7,500 | Achieved |
When goals miss, understanding why shapes more realistic planning: unrealistic target? Unexpected expenses? Income shortfall?
Next Year Planning
Based on your review:
- Adjust categories that were consistently off
- Account for known changes
- Build in buffer for unknowns
- Schedule quarterly reviews while motivation is fresh
Common Findings
Categories often underestimated: dining and entertainment, subscriptions, home maintenance, pet expenses, gifts.
Categories often under budget: clothing (after first year), household supplies, personal care.
Expenses frequently forgotten: annual insurance premiums, property taxes, vehicle registration, professional dues. For a fuller list, see the budget categories people forget.
Once the review is done, the next move is to carry the findings into a fresh plan. Each copy of the Annual Budgeting Planner covers one year on a single 12-month plan and actual grid, with a Categories tab where the category list is edited once and applies across the template. A new year means a new copy, so last year’s figures stay in last year’s file. The year-end financial review questions cover the reflection side that numbers alone miss.
Related
- Annual Budgeting Planner - Full year view
- Financial Planning Template - Long-term projections
- Net Worth Tracker - Monthly balances and YTD change
- Monthly budget vs annual budget - Which view fits your habits
- Best free annual budget templates - Free starting points
Frequently asked questions
When should I do this review?
Late December or early January works well. Finalize the current year while planning next.
What if I didn't track all year?
Pull bank and credit card statements. Categorize retrospectively. Use this as baseline for next year.
How detailed should it be?
Balance thoroughness with sustainability. A completed simple review beats an abandoned complex one.
Should my partner participate?
If you share finances, absolutely. This is an important alignment conversation.
Which 2026 contribution limits should I check my retirement accounts against?
For 2026 the 401(k) employee deferral limit is $24,500 and the IRA limit is $7,500, both higher than 2025. Utilization percentages in this checklist assume the current-year cap, so the limits move each year and the target does too.
Is a year-end budget review the same as reconciling my accounts each month?
No. Monthly reconciliation confirms transactions cleared and categories are current. The annual review steps back to look at 12 months of totals, trends, and year-over-year changes that a single month can't show.
Sources
- 401(k) limit increases to $24,500 for 2026, IRA limit increases to $7,500 - Internal Revenue Service
About this article
Retirement contribution limits checked against IRS Notice 2025-67 (2026 401(k) and IRA figures) Template sheets, inputs and outputs checked on 2026-09-10 against the shipped Annual Budgeting Planner (Summary, Annual Plan, Annual Financial Goals, Categories tabs), Net Worth Tracker (Summary, Assets, Liabilities, Milestones tabs) and Financial Planning (Goals, Assets, Debt, Cashflow, Projection tabs) Google Sheets Last reviewed September 2026.