Coast FIRE is the amount invested today that will grow to fund a traditional retirement with no further contributions. The formula is Coast FIRE = retirement target / (1 + r)^n, where r is the real annual return and n is years to retirement. A 35 year old targeting $1.25M at 65 at a 7 percent real return needs about $164,000 today. Below: the formula, three worked examples at ages 28, 35, and 45, and a free calculator for your own numbers.
The Coast FIRE concept is simple, but the math behind it gets glossed over in most explainers. This post publishes the actual formula and walks three worked examples at different ages and income levels, with a free calculator below so you can plug in your own numbers. Our free FIRE Financial Freedom Calculator spreadsheet answers the related question of when your savings reach financial freedom.
The formula
The Coast FIRE number is the present value of your retirement target, discounted by the rate of return over the years until retirement.
Coast FIRE Number = FV / (1 + r)^nWhere:
FVis your retirement target (typically 25 times your annual retirement spending, per the 4 percent rule)ris your assumed real annual return (commonly 5 to 7 percent after inflation)nis the number of years from today until retirement
In plain English: how much money do I need invested right now so that, with no further contributions, compounding grows it to my retirement target by the time I want to retire?
Hit that number and you’ve reached “coast.” You can stop saving for retirement and let the existing balance grow on its own. You still have to cover your current living expenses, but the future is funded.
Why this matters
There are two related questions in retirement planning, and most calculators only answer one.
Question 1: How much do I need to retire? (Answered by 25x annual expenses, or whatever variation of the 4 percent rule you prefer.)
Question 2: How much do I need today so that compounding alone gets me there? (This is Coast FIRE.)
The second question is more useful for younger savers because it converts a distant intimidating number ($1.5M at 65) into a near-term concrete one ($150K at 35). Hitting $150K feels possible. Hitting $1.5M feels mythical. Coast FIRE is just a different framing of the same problem, and the framing changes behavior.
Coast FIRE vs full FIRE
Coast FIRE and full FIRE answer different questions, and it helps to see them side by side. Full FIRE is the point where you can stop working entirely. Coast FIRE is the earlier point where you can stop saving for retirement while you keep earning to cover today’s expenses.
| Coast FIRE | Full FIRE | |
|---|---|---|
| Goal | Stop saving for retirement | Stop working entirely |
| Portfolio needed | Fraction of the final target | Full 25x expenses |
| After reaching it | Keep earning for current expenses | Optional work only |
| Timeline | Reachable in 5 to 15 years for many | Often 15 to 25+ years |
| Risk | Market returns may differ from projections | Sequence of returns, inflation |
Some people find Coast FIRE more motivating because the milestone is closer. Others treat it as a waypoint on the path to full financial independence.
Three worked examples
Same retirement target ($1.25M, based on $50K annual spending at the 4 percent rule), three different ages, same 7 percent real return assumption.
Example 1: 28 year old
- FV = $1,250,000
- r = 0.07
- n = 37 (retire at 65)
(1.07)^37 = 12.22
Coast FIRE = 1,250,000 / 12.22 = $102,260
A 28 year old with $102,260 invested in a low-cost diversified portfolio, who never adds another dollar to retirement accounts, will have $1.25M at 65 if real returns average 7 percent.
Example 2: 35 year old
- FV = $1,250,000
- r = 0.07
- n = 30
(1.07)^30 = 7.61
Coast FIRE = 1,250,000 / 7.61 = $164,260
The same target, seven years later. The Coast FIRE number jumped about 60 percent because compounding has fewer years to work.
Example 3: 45 year old
- FV = $1,250,000
- r = 0.07
- n = 20
(1.07)^20 = 3.87
Coast FIRE = 1,250,000 / 3.87 = $322,990
By 45, the Coast FIRE number is more than triple what it was at 28. This is the cost of waiting, expressed as a single number.
Coast FIRE numbers by age and spending target
The three examples above share one spending assumption. Widening it out, here is how the number moves across ages and retirement spending levels, all at 7 percent real return and a retirement age of 65. The $75K column is 1.5 times the $50K target; the $100K column is double it.
| Age | $50K/year ($1.25M) | $75K/year ($1.875M) | $100K/year ($2.5M) |
|---|---|---|---|
| 25 | $83,500 | $125,300 | $167,000 |
| 30 | $117,000 | $175,500 | $234,100 |
| 35 | $164,200 | $246,300 | $328,400 |
| 40 | $230,200 | $345,300 | $460,400 |
Read across any row and the cost of a bigger retirement shows up; read down any column and the cost of waiting does. At 25 a $50K retirement coasts on $83,500. At 40 the same target needs $230,200, nearly three times as much.
What changes if you use different assumptions
The 7 percent real return is the historical US stock market average over long periods, after inflation. It’s a reasonable default but not the only choice.
| Real return | Coast FIRE at 35 (target $1.25M, 30 years) |
|---|---|
| 5 percent | $289,300 |
| 6 percent | $217,650 |
| 7 percent | $164,260 |
| 8 percent | $124,440 |
A 1 percent change in your return assumption shifts the number by roughly 25 percent. This is the single biggest source of variance in Coast FIRE estimates. People who use 5 percent are being conservative; people who use 8 percent are being aggressive. The honest answer is somewhere in the middle and you don’t get to know in advance.
The same sensitivity applies to your retirement spending estimate. $50K annually means a $1.25M target. $60K means $1.5M (and a 20 percent higher Coast FIRE number). Be honest about your spending; lowballing it is the most common error and the most expensive one to discover at 60.
What Coast FIRE doesn’t tell you
It’s a forecast, not a promise. The 7 percent real return assumption smooths over 30 years of market volatility that, in any given decade, can mean negative real returns. Sequence-of-returns risk is real: a 50 percent crash in years 1-3 changes the picture even if the long-run average works out.
Three caveats worth knowing:
It assumes static spending. If your retirement lifestyle inflates with your income (a common pattern), the target grows with you and you might find yourself behind on a moving target.
It doesn’t account for healthcare or unusual events. A long-term care need or a major medical expense in retirement can shift the target meaningfully. The base 25x rule is for a “typical” retirement.
It assumes the money is invested in something close to a market portfolio. Coast FIRE on $164K in a checking account doesn’t work. The math depends on actual investment returns, which require actually being invested.
For a more cautious view, drop your real return assumption to 5 percent and increase your target by 25 percent. If the resulting Coast FIRE number still feels reachable, you have meaningful margin.
How to use the free calculator
The on-site Coast FIRE Calculator runs the math in your browser. Inputs:
- Current savings (your invested balance today)
- FIRE number (your retirement target, usually 25x annual spending)
- Current age
- Retirement age (defaults to 60)
- Expected return (defaults to 7 percent)
It returns your Coast FIRE number, a coast age that reads “Now” when your current balance already clears that number, projected value at retirement, and a year-by-year chart plotting your savings growth and the Coast FIRE path against a flat FIRE target line.
The figure to watch over time is the gap between your current invested balance and this number. The Coast FIRE number climbs as you age, because fewer compounding years remain to do the work, and an invested balance tends to climb as well. The point where the balance catches the number is where what is already on hand can coast to the target on its own. When you add up your current invested total, the usual approach counts retirement accounts and long-term brokerage holdings, not an emergency fund or money earmarked for spending before retirement.
For the general FIRE number (how much you need to retire outright, not just coast), the free FIRE Financial Freedom Calculator spreadsheet takes monthly savings, monthly expenses, current savings, a yearly return and an inflation rate, then reports the year and the age at which you reach financial freedom, with a year-by-year table behind it. If you want a fully built retirement projection (one combined savings balance, an annual savings figure, pension income with its own start age, and a year-by-year withdrawal projection across conservative, base and optimistic scenarios), our paid Retirement Financial Planning Projections template covers that. Coast FIRE is a single input on a much larger picture; the on-site calculator handles the standalone question.
Coast FIRE vs other FIRE flavors
Quick definitions because the terminology trips people up.
| Type | Definition | Number for $50K retirement |
|---|---|---|
| Lean FIRE | Retirement on minimal expenses ($25K-$40K/yr) | $625K-$1M |
| Regular FIRE | 25x annual spending | $1.25M |
| Fat FIRE | Comfortable to luxurious retirement ($100K plus/yr) | $2.5M plus |
| Coast FIRE | Enough invested today to coast | Varies by age |
| Barista FIRE | Partial retirement with side income | Varies |
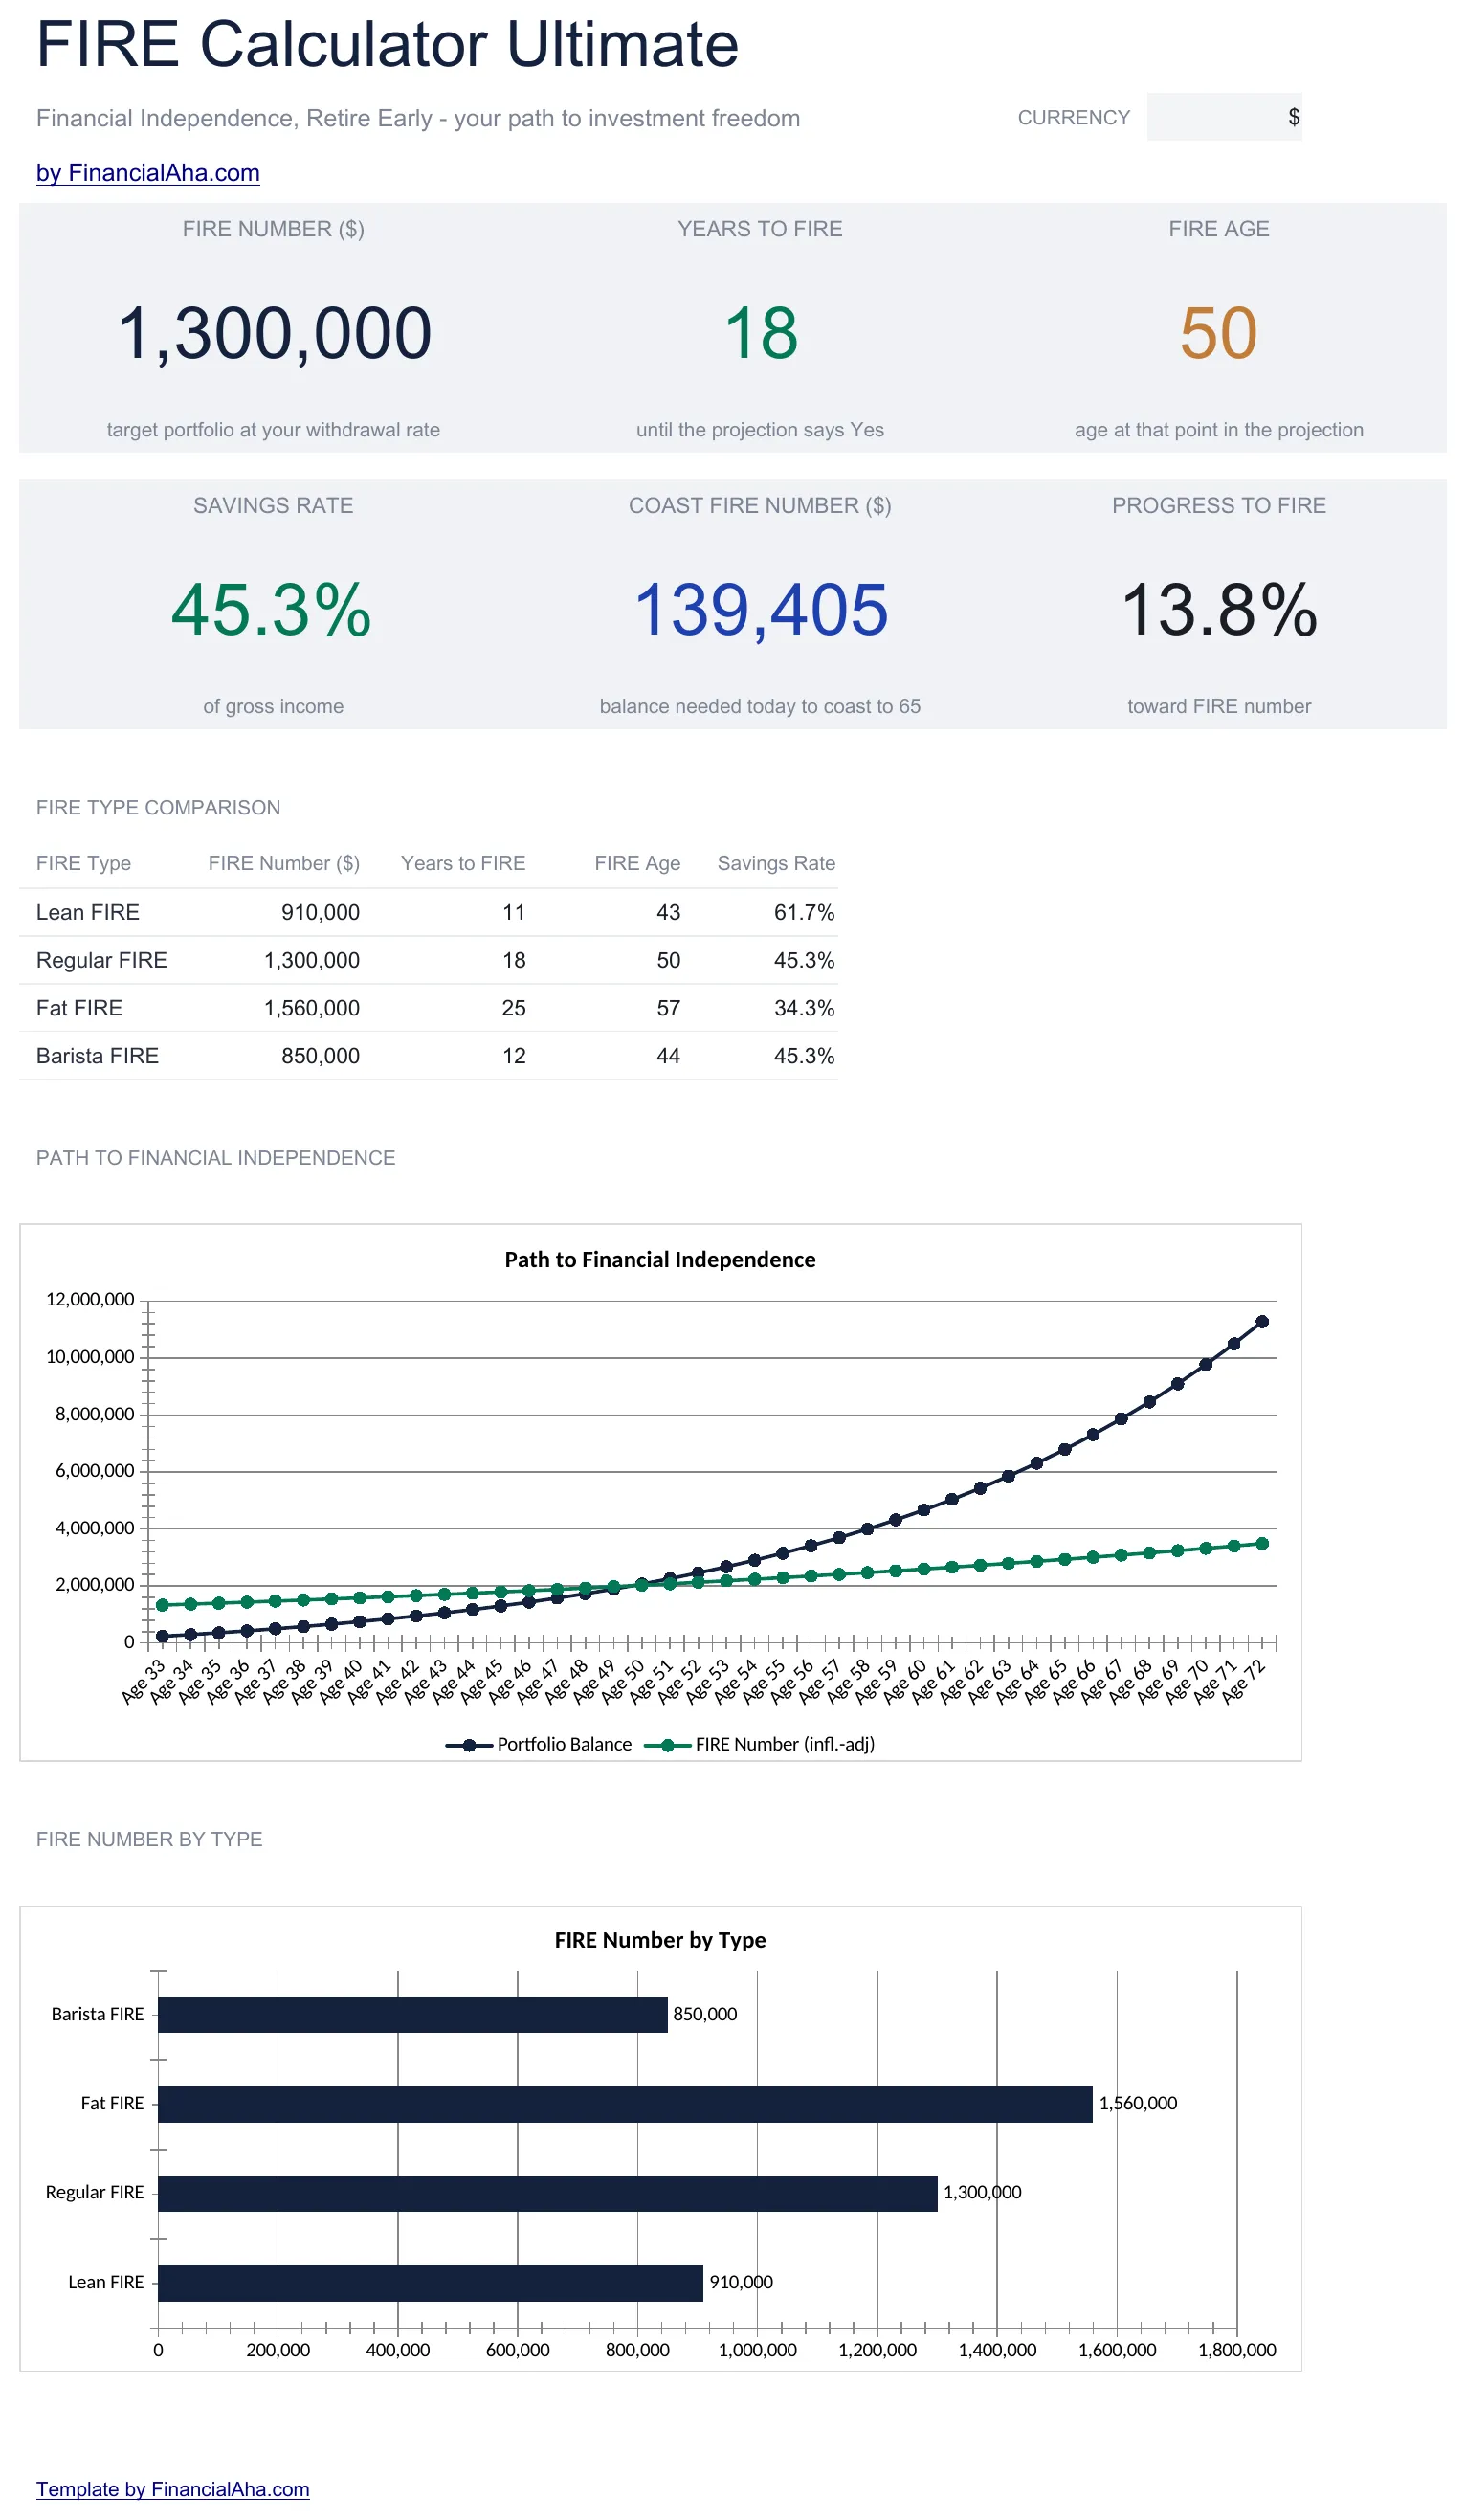
The FIRE Calculator Ultimate ($29) puts the Coast FIRE number next to Lean, Regular, Fat, and Barista FIRE and charts the point where your projected balance crosses the target.
For more on the distinctions and what each implies for your savings rate, see Lean FIRE vs Fat FIRE vs Coast FIRE: What the Numbers Actually Are.
A practical takeaway
If you’re under 40 and your invested balance is already past your Coast FIRE number for a reasonable target, you’ve earned the option to redirect future income. That doesn’t mean you should stop saving. It means you no longer need to.
For a 28 year old who hits Coast FIRE at about $102K, the next decade of savings becomes optional. They might invest it anyway (more cushion), they might use it for a career pivot, or they might shift to a lower-paying job that fits better. The math gives them the choice.
That’s the whole point of running the number.
Get the template
- FIRE Financial Freedom Calculator - the year and age your savings reach financial freedom, from your savings, expenses, return and inflation. Free, no signup.
- Retirement Financial Planning Projections - year-by-year retirement withdrawal projection with configurable return, inflation and pension assumptions.
- FIRE Calculator Ultimate ($29) - Lean, Regular, Fat, Barista and Coast FIRE numbers on one dashboard, with a year-by-year chart of balance against target.
Related
- Coast FIRE Calculator - run your own numbers in the browser
- FIRE Calculator: How to Calculate Your Financial Independence Number
- FIRE Calculators and Spreadsheets Compared
- Retirement Calculator: How Much Do You Actually Need?
- FIRE Financial Freedom Calculator - free Google Sheets template
Frequently asked questions
What return assumption should I use for Coast FIRE?
7 percent real (after inflation) is the common default, based on long-run US stock market history. 5 to 6 percent is more conservative. The variance in your final number from this single choice is large, so it's worth running both ends to see the range.
Does Coast FIRE include Social Security?
The standard formula doesn't. Some people treat Social Security as bonus margin; others lower their retirement target to account for expected benefits, which lowers the Coast FIRE number. Both are valid approaches.
Is Coast FIRE realistic on an average income?
Depends on age and starting point. A 25 year old saving 15 percent of a $60K income can hit Coast FIRE for a moderate target by their early 30s. A 45 year old starting from zero faces a much steeper climb. The math is age-sensitive in a non-linear way.
Can I Coast FIRE in my 20s?
Mathematically, it's the easiest age to do it because compounding has the most years to work. Practically, hitting about $102K invested by 28 requires an early start, a habit of saving, and either a strong income or an unusually low cost of living.
How does Coast FIRE relate to the 4 percent rule?
The retirement target in the formula typically uses 4 percent rule logic (25x annual spending) as the future value. Coast FIRE answers what you need today for compounding to reach that target. They're complementary, not competing.
Sources
- Compound Interest Calculator - U.S. Securities and Exchange Commission (Investor.gov)
- Consumer Price Index - U.S. Bureau of Labor Statistics
About this article
Every worked example and table figure was recomputed from the present-value formula Coast FIRE = target / (1 + r)^n. Real-return and inflation framing checked against U.S. Bureau of Labor Statistics CPI data and the SEC's Investor.gov compound interest calculator. Template sheets, inputs and outputs checked on 2026-09-10 against the shipped FIRE Financial Freedom Calculator (Freedom tab), the Retirement Financial Planning Projections Google Sheet (Summary, Inputs, Projections tabs) and the FIRE Calculator Ultimate workbook (Dashboard, Assumptions, FIRE Projection, FIRE Types, Coast FIRE, Withdrawal Strategy tabs). Last reviewed September 2026.